

1. Scorecard
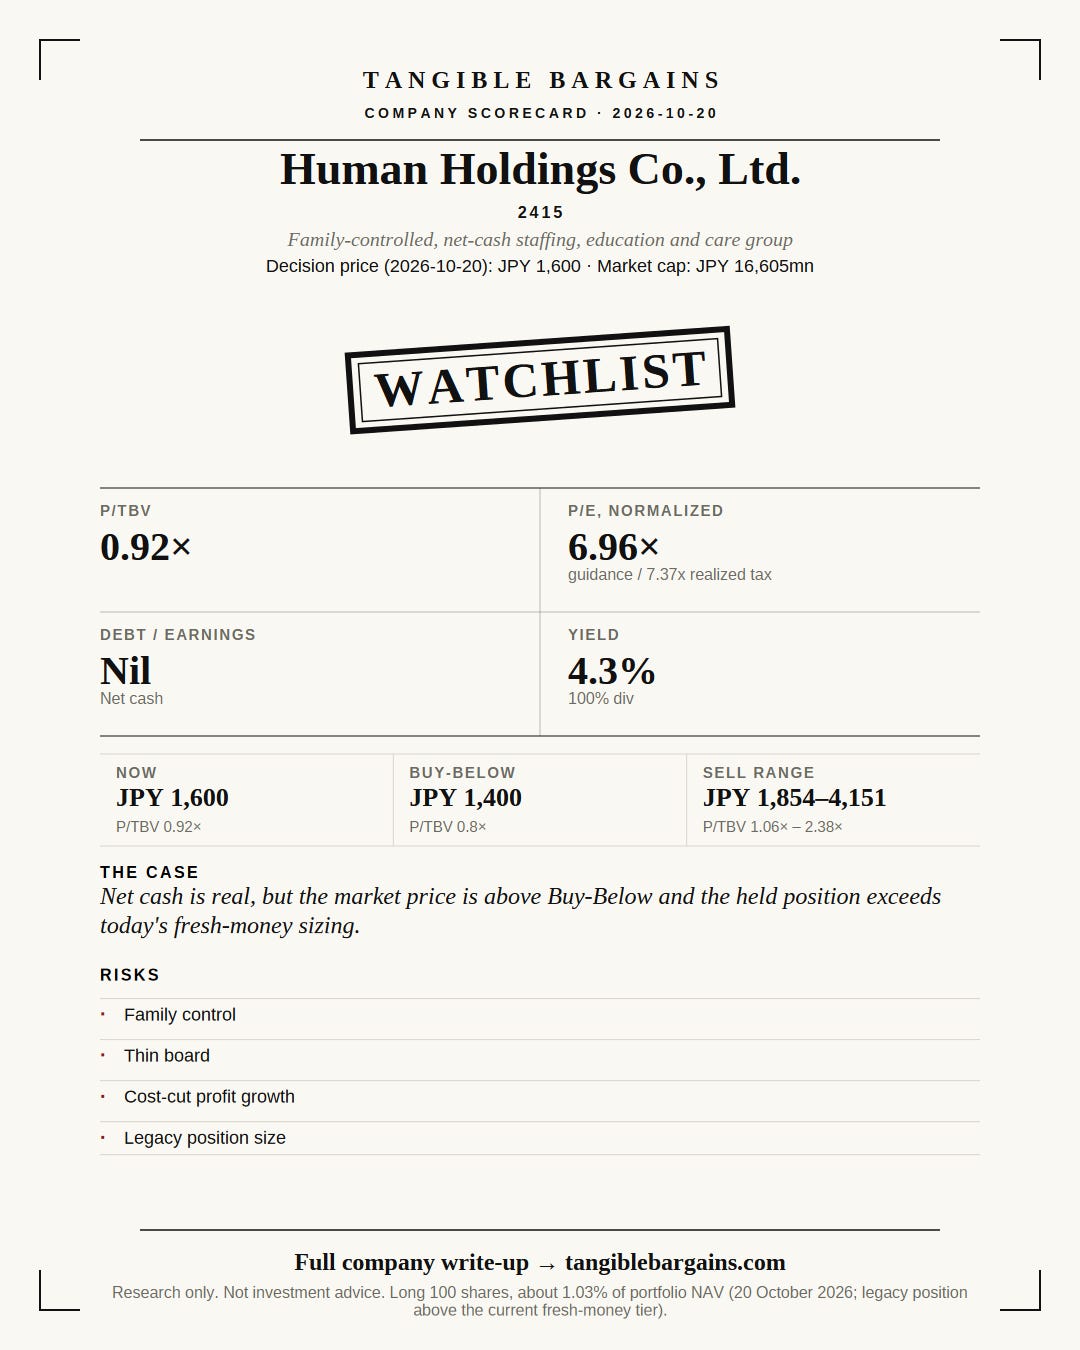
Verdict: WATCHLIST.
Actionable now: No — accumulate at ≤ JPY 1,400 (price JPY 1,600 as of 20 October 2026).
Position: Long 100 shares, about 1.03% of portfolio NAV (20 October 2026; legacy position above the current fresh-money tier).
2. Argument
The short version
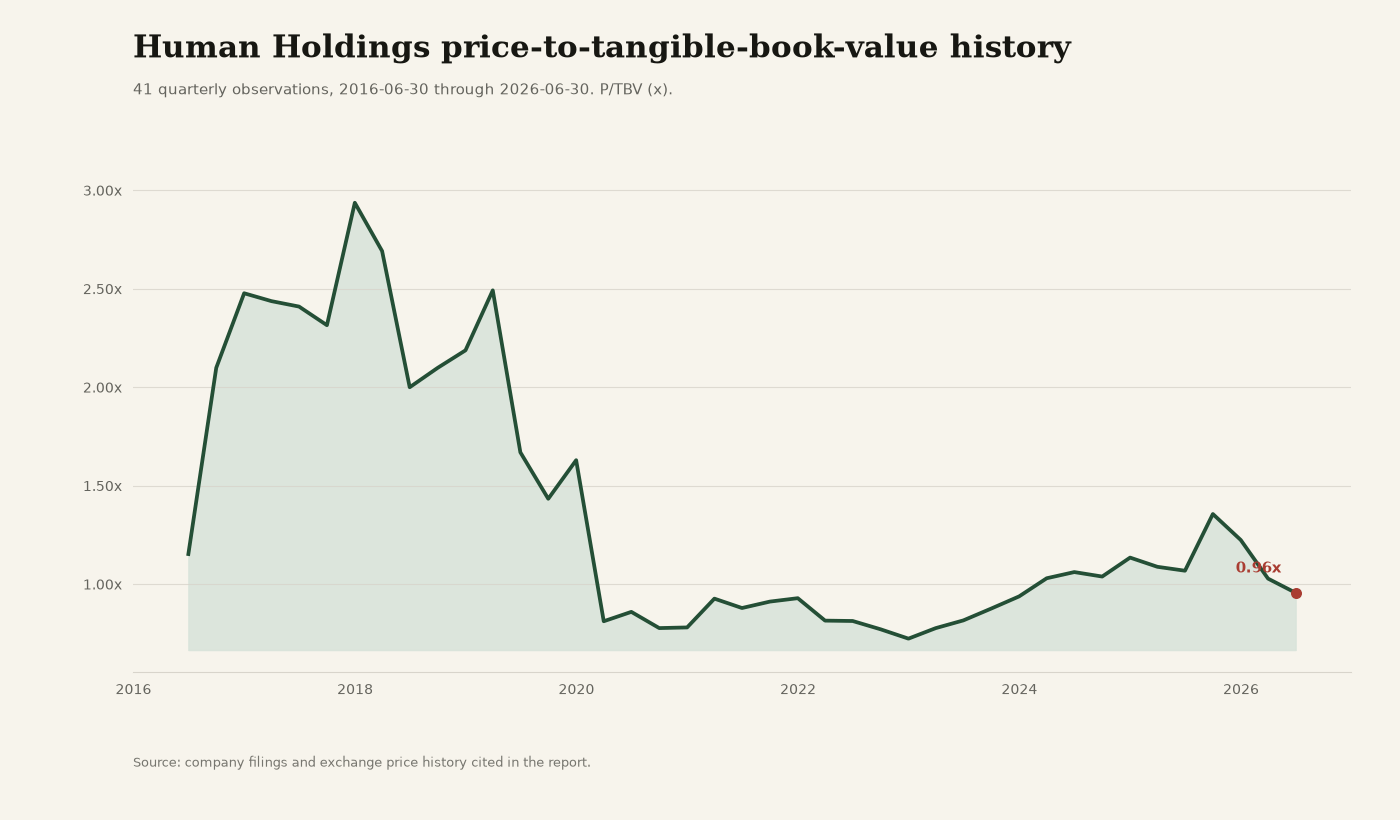
Human Holdings combines staffing, education and elder care. At JPY1,600 on 20 October 2026 it trades at 0.92× tangible book, but above the JPY1,400 Buy-Below. The public decision is WATCHLIST: hold the legacy 100-share position, do not add fresh money here.
Net cash is the attraction, with one important qualification: JPY9.89bn of cash is matched by prepaid-tuition contract liabilities and is not freely distributable surplus. Family control and a thin board add a second discount.
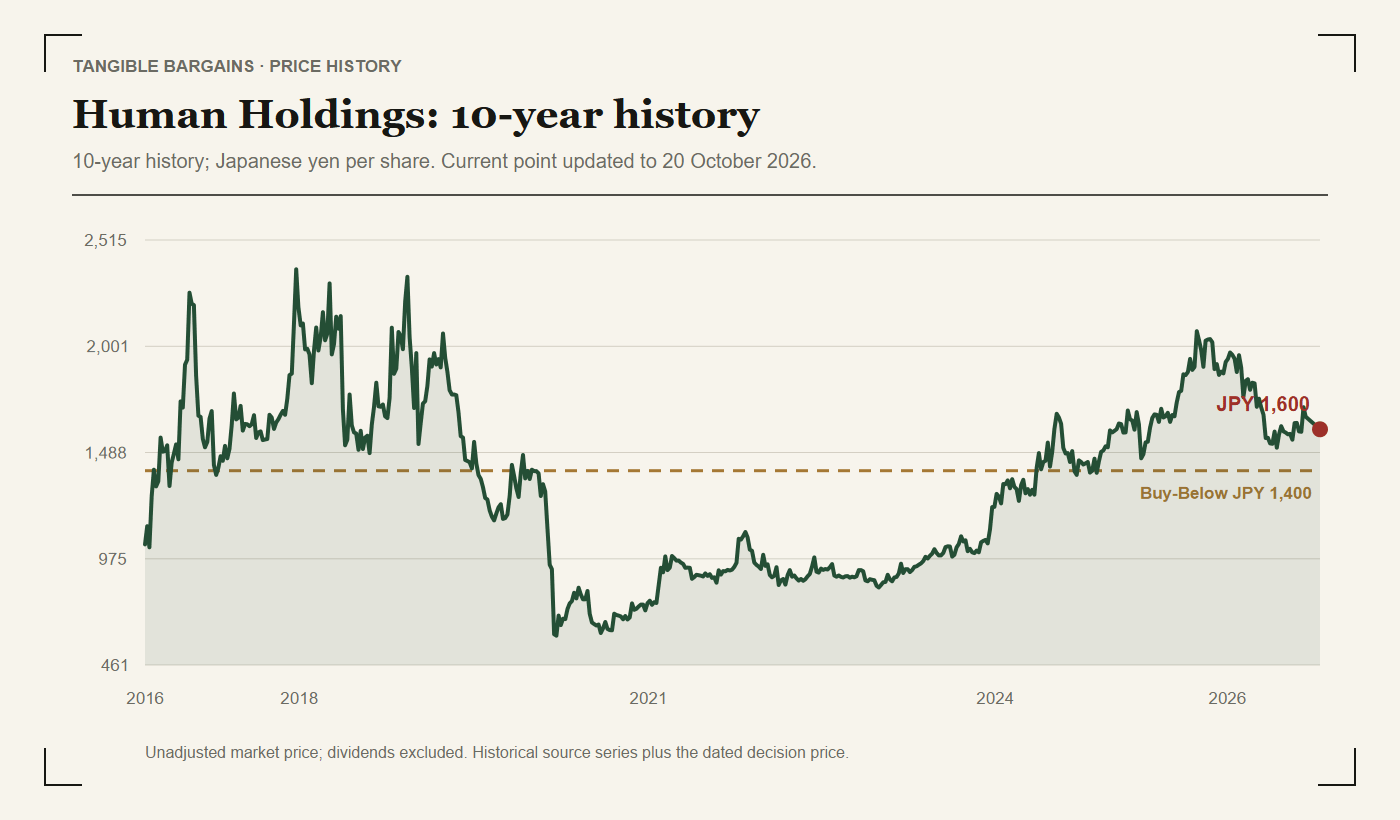
The ten-year history shows where the dated decision price sits. It is context for valuation, not evidence that a fallen share must rebound.
A service conglomerate with uneven economics
Staffing supplies most profit; education and nursing care are smaller, labor-intensive businesses. Japan's labor shortage and aging population help demand, but the vocational-school operation faces a shrinking youth population. This is a stable service group, not a high-return compounder.
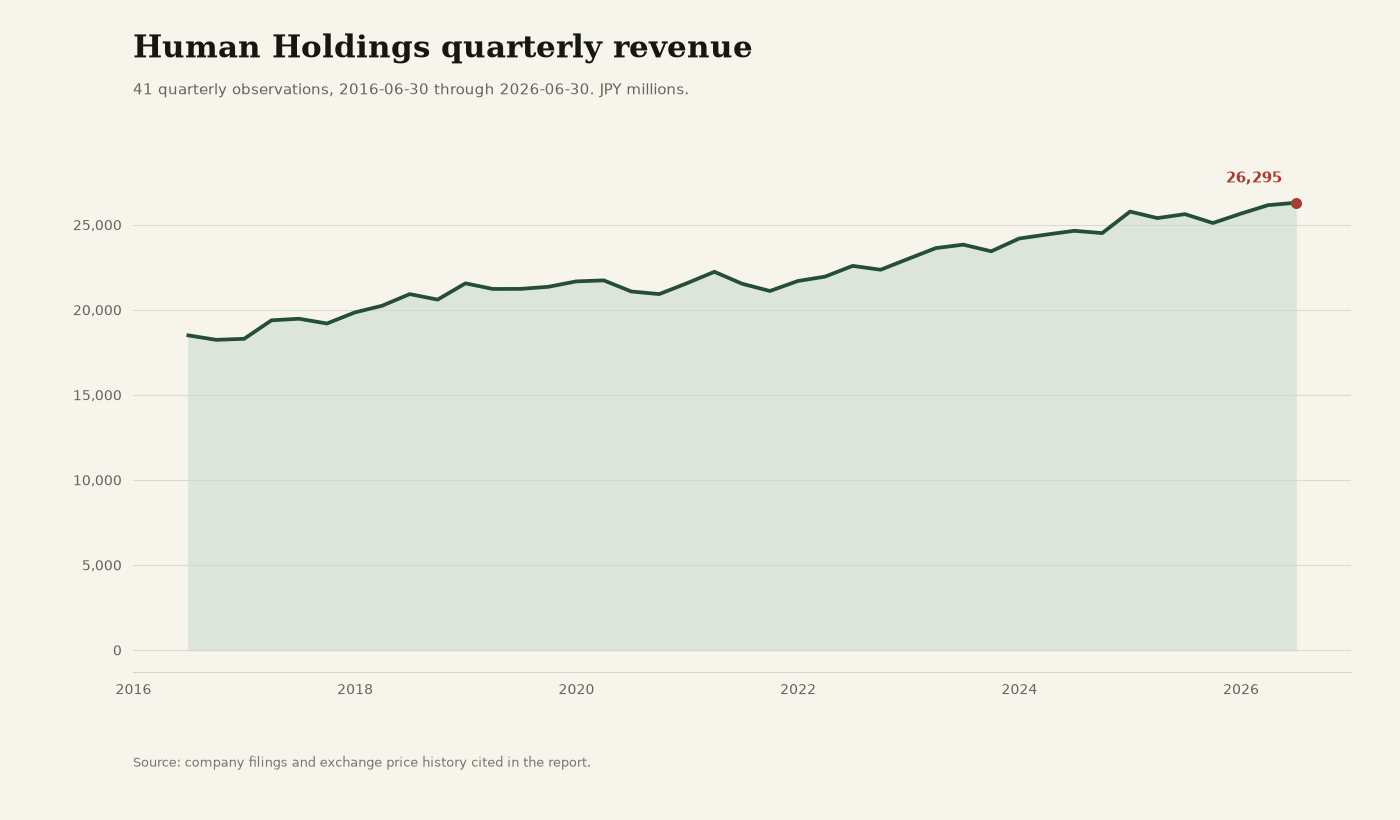
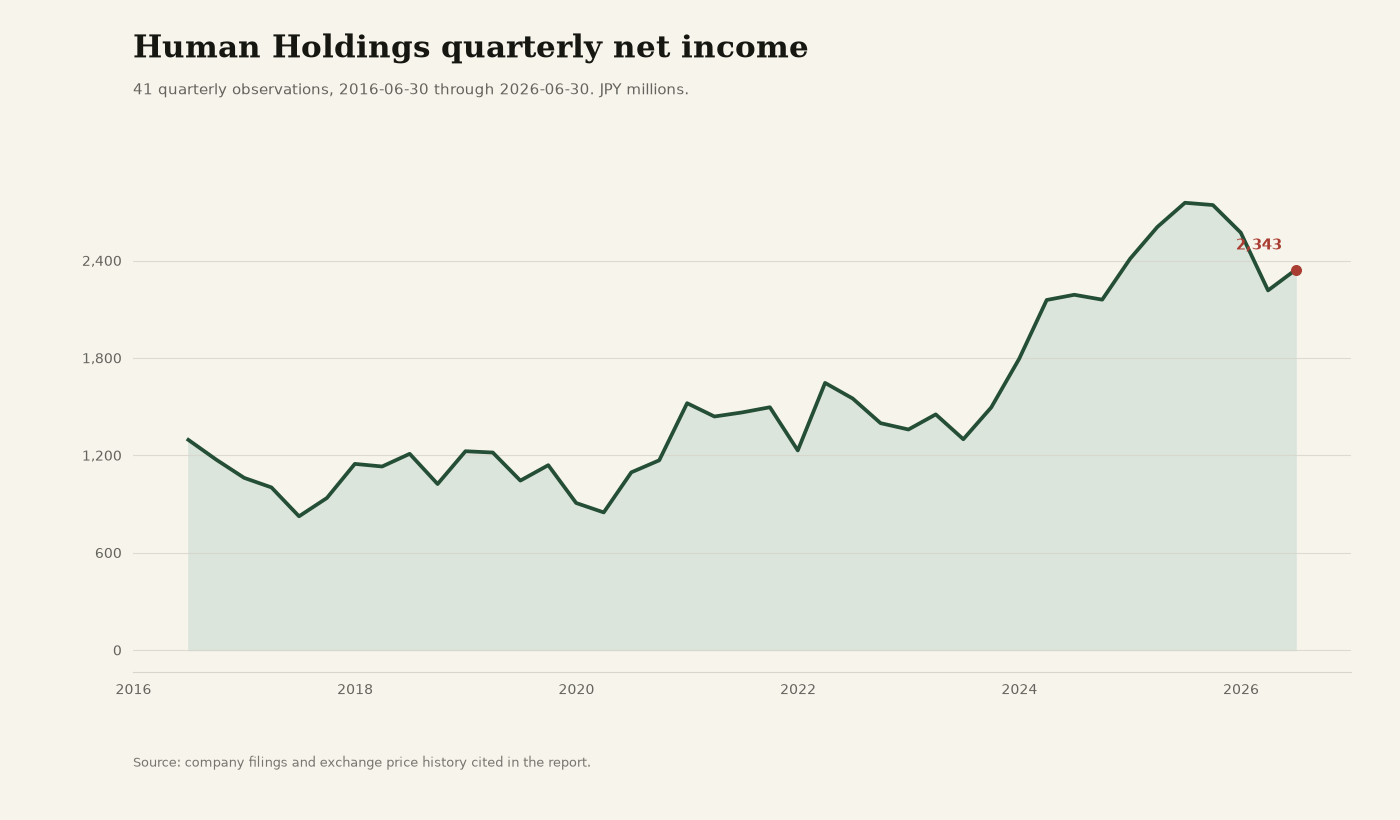
Net cash remains real and goodwill is negligible. Last year's operating-profit improvement was less impressive than the headline: 117% came from lower advertising and bonus costs, while underlying costs grew faster than gross profit. The bonus reduction is already reversing, and the effective tax rate rose 8.3 points. Funded debt also rose 14.6% in one quarter without a retrieved filing explaining why.
The control range
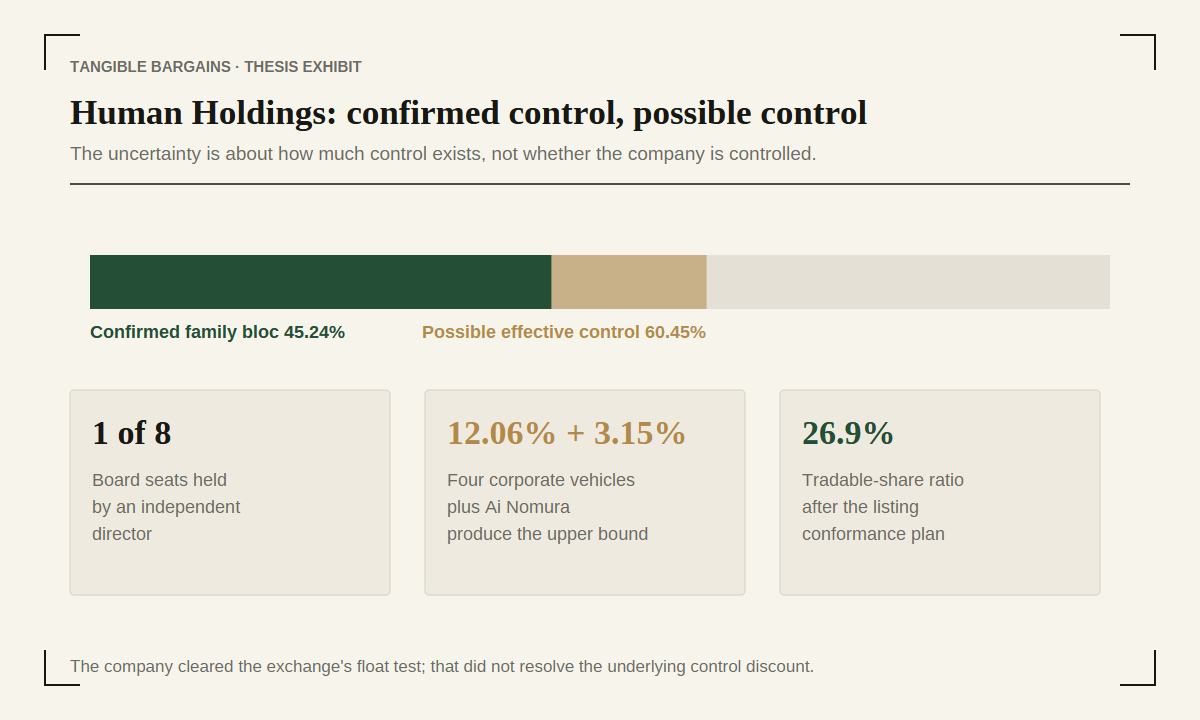
The family bloc is confirmed at 45.24%. Four corporate vehicles add 12.06% if affiliated, producing 57.30%; a separate 3.15% Ai Nomura affiliation is also required to reach the conditional 60.45% upper bound.
Only one of eight directors is independent. Earlier share-retirement and float-widening actions were driven by exchange listing rules and involved officers and relatives, so another tender offer cannot be assumed. The balance sheet can fund patience; it does not guarantee that minorities receive the cash.
What could change the view
The next two results should show whether the tax rate and reversing bonus cut behave as guided and explain the quarterly debt increase. Confirmation of the corporate vehicles and Ai Nomura relationship, or a tender offer that is not merely a listing-compliance exercise, would improve the control case. A weakening staffing spread or further cost-led profit growth would do the opposite.
Sources and gaps
The report uses the annual and interim filings and two primary exchange notices. Officer compensation, the detailed quarterly debt explanation and the identity of some large shareholders remain unconfirmed.
3. Numbers that matter
The current price is JPY1,600, Buy-Below JPY1,400, and Sell Range JPY1,854–4,151; tangible book is about JPY1,742 per share. Net cash is roughly JPY19.8bn, but JPY9.89bn of cash is matched by prepaid-tuition contract liabilities. The family bloc is 45.24%; four vehicles could bring it to 57.30%, and a separate 3.15% Ai Nomura affiliation is required for the conditional 60.45% upper bound. Only one of eight directors is independent.
Research only, not investment advice.