

1. Scorecard
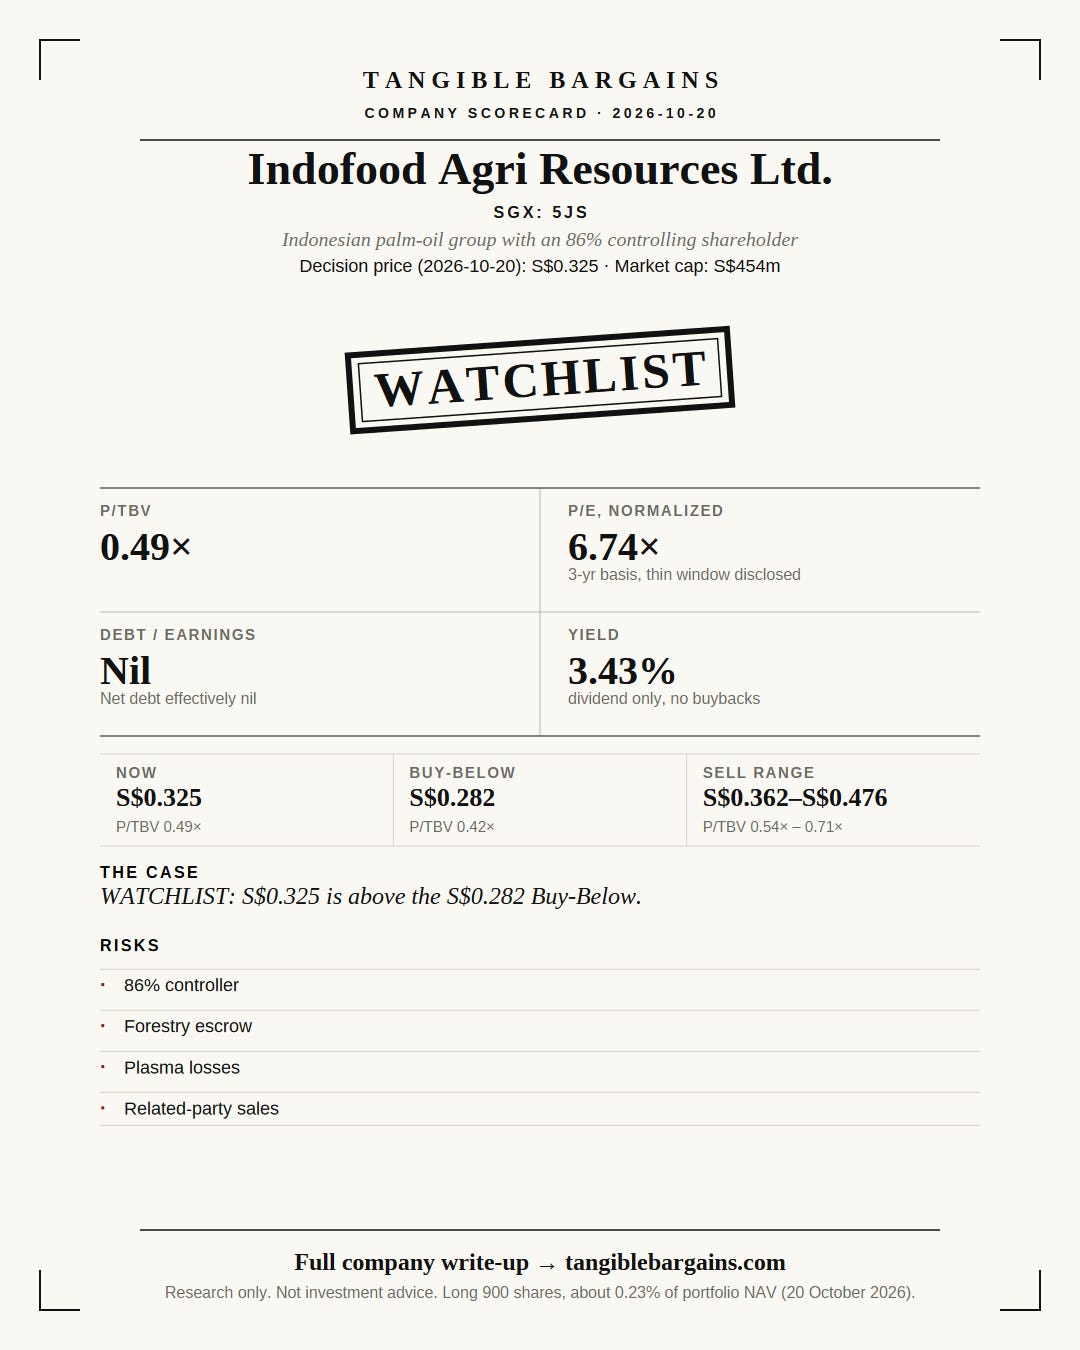
Verdict: WATCHLIST.
Actionable now: No — accumulate at ≤ S$0.282 (price S$0.325 as of 20 October 2026).
Position: Long 900 shares, about 0.23% of portfolio NAV (20 October 2026).
2. Argument
The short version
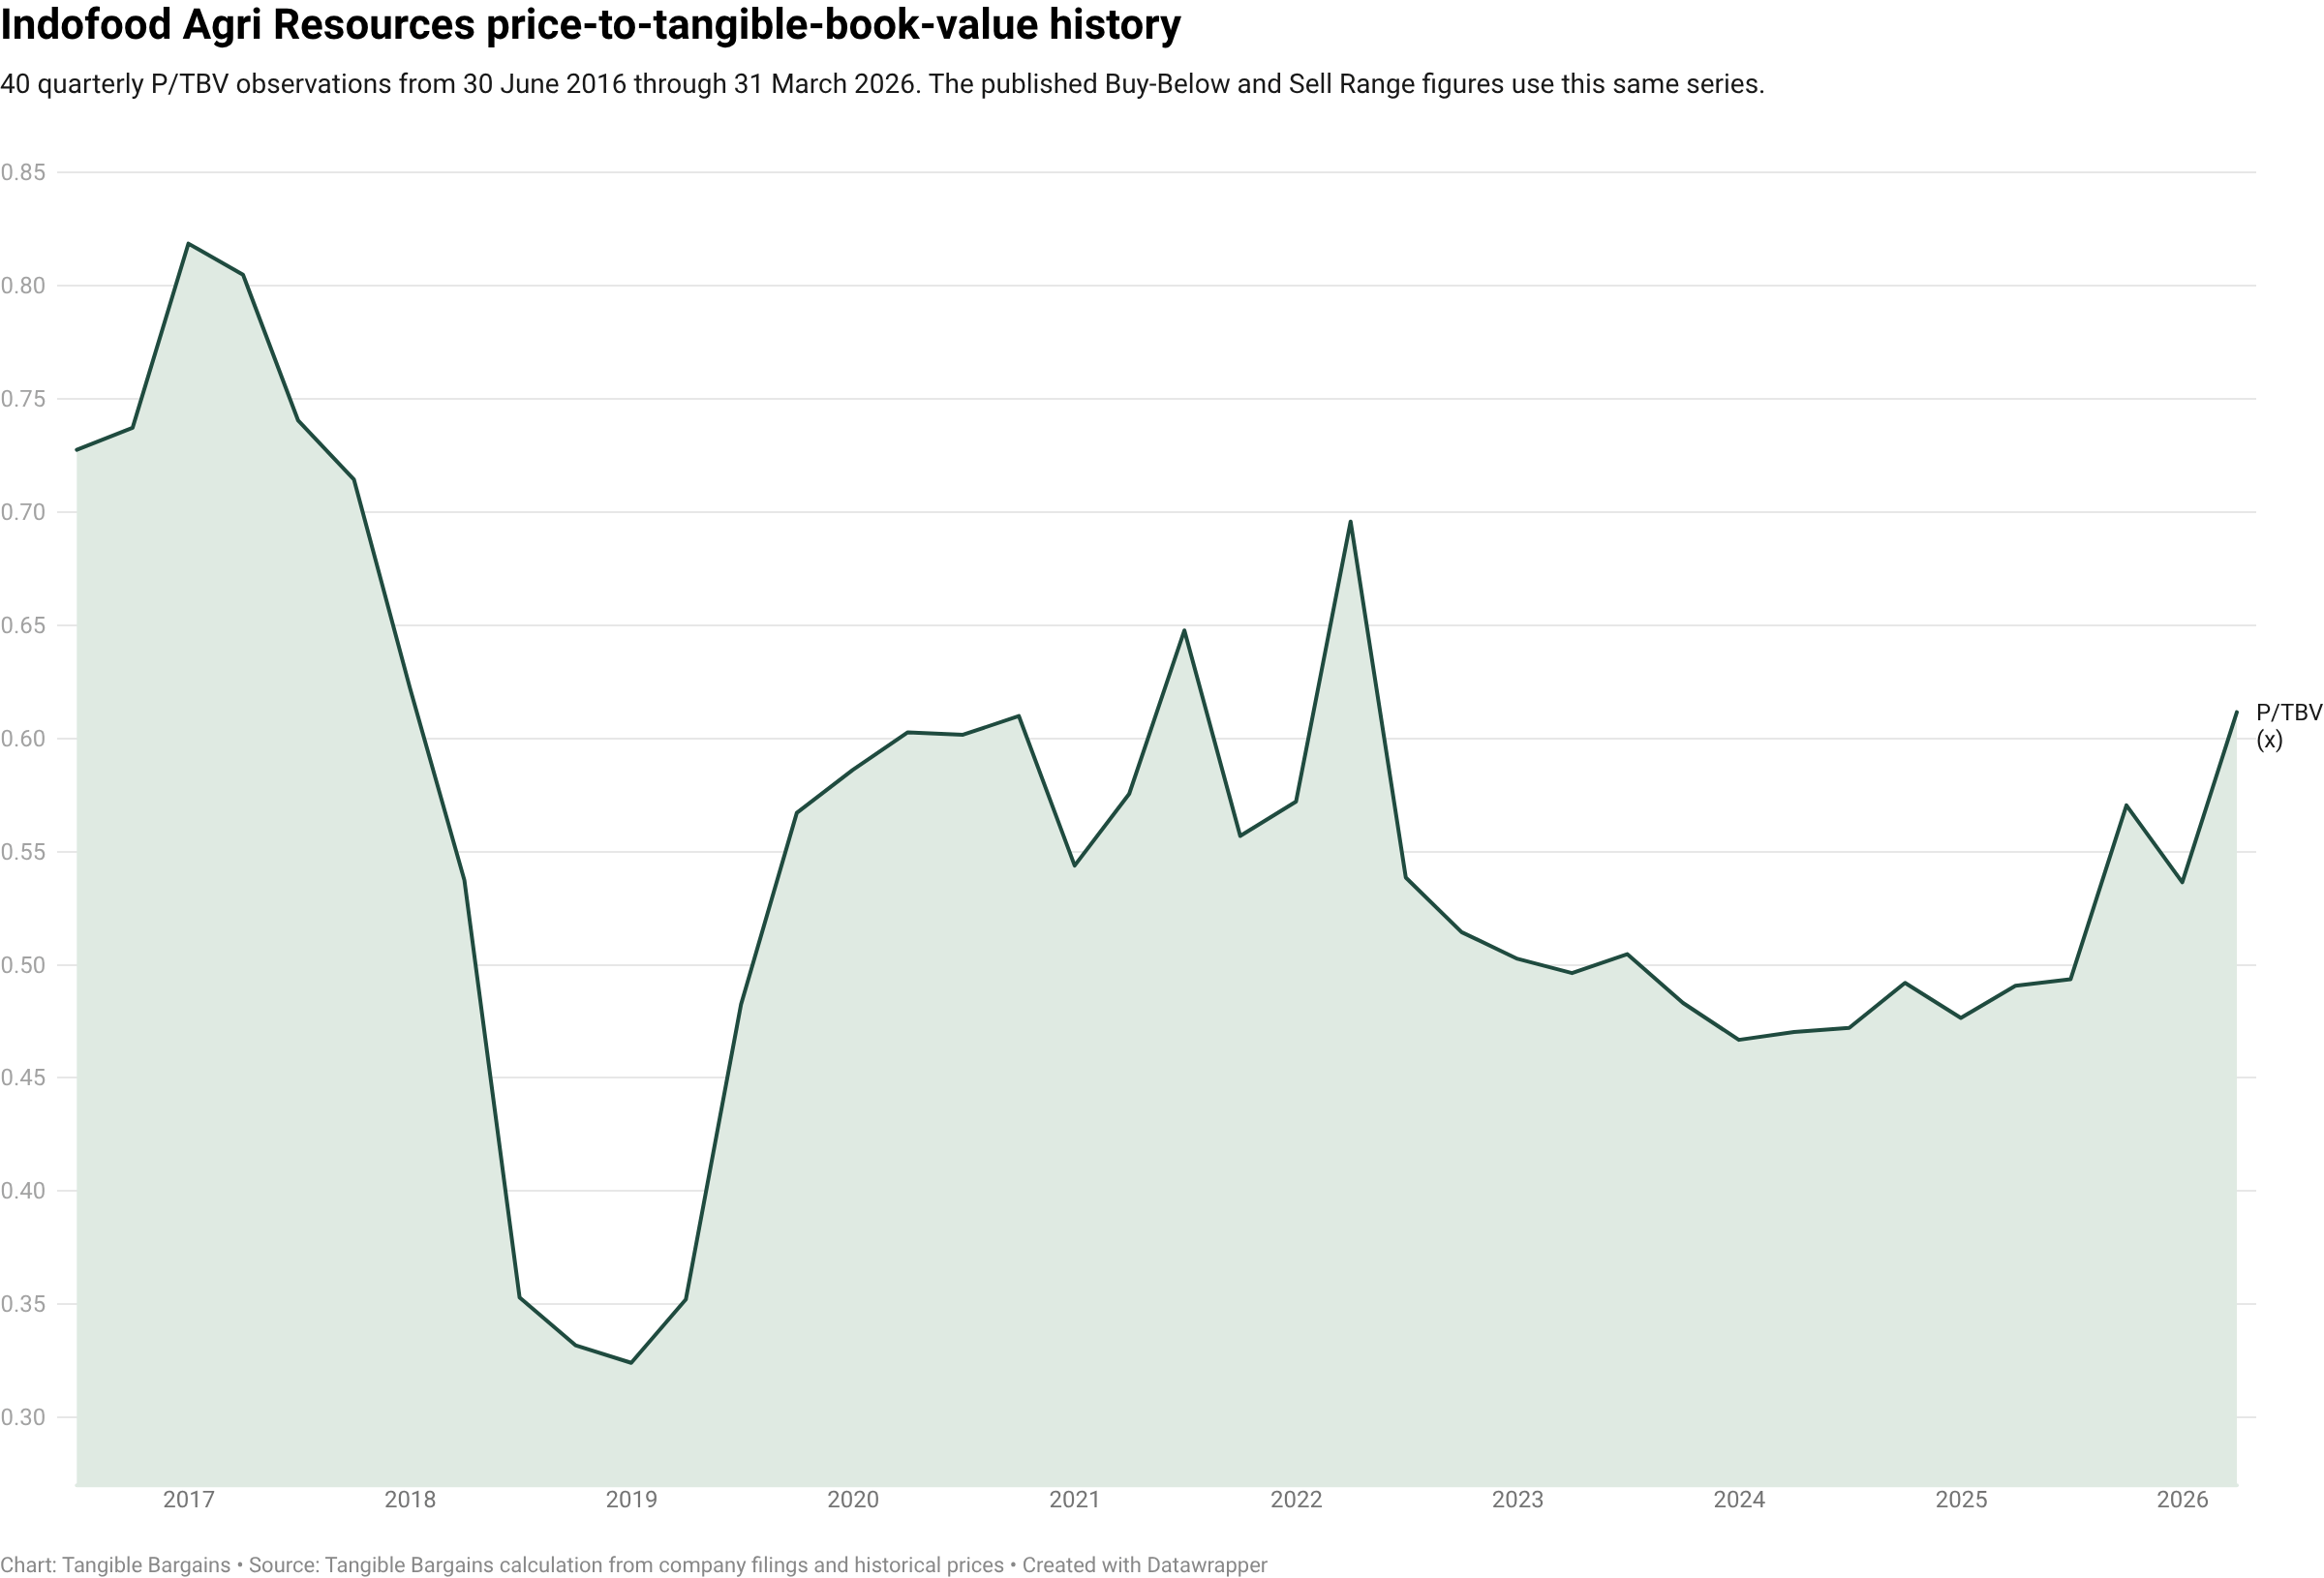
Indofood Agri Resources is a Singapore-listed wrapper around a large Indonesian palm-oil group. At S$0.325 on 20 October 2026 it trades below half of tangible book, but above the S$0.282 Buy-Below. The public decision is WATCHLIST: hold the existing 900 shares, add only at the lower price.
The balance sheet is close to net cash and the operating recovery is real. The reason the stock stays cheap is control. The Salim family is deemed interested in 86.04%, the float is thin, and minority holders do not receive every asset or cash flow shown in the consolidated accounts.
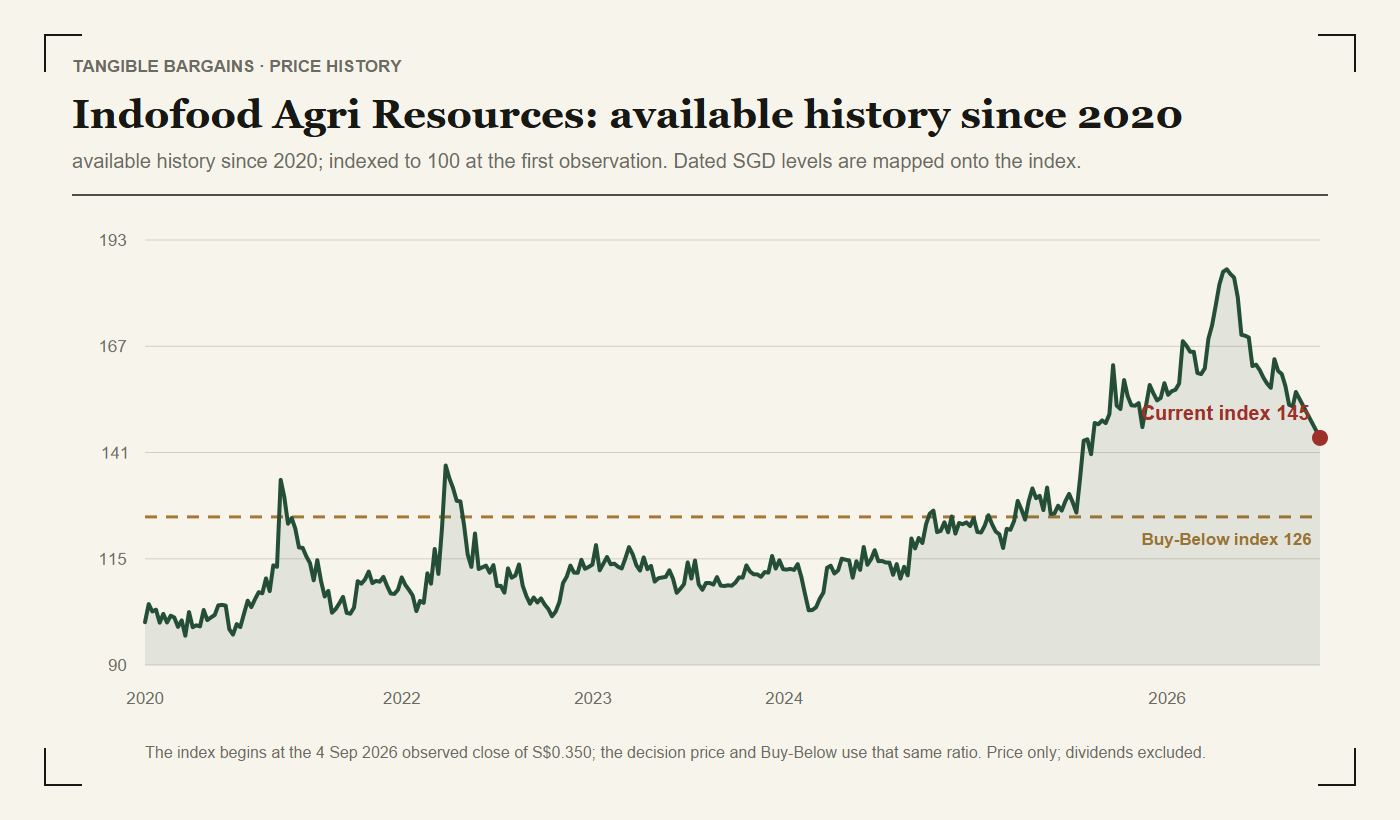
The available history is in rupiah, so this exhibit uses an index. It begins at the 4 September 2026 observed close of S$0.350; the decision price and Buy-Below use that same ratio.
A plantation and refinery system
IndoAgri controls 278,099 planted hectares, 27 palm-oil mills and five refineries. About 97% of revenue is earned in Indonesia. Plantations benefit from palm-oil prices and estate yields; refineries add processing and branded-product margins. The vertical integration helps supply, but 94% of first-half CPO volume moved internally, so reported segment economics are not wholly arm's-length.
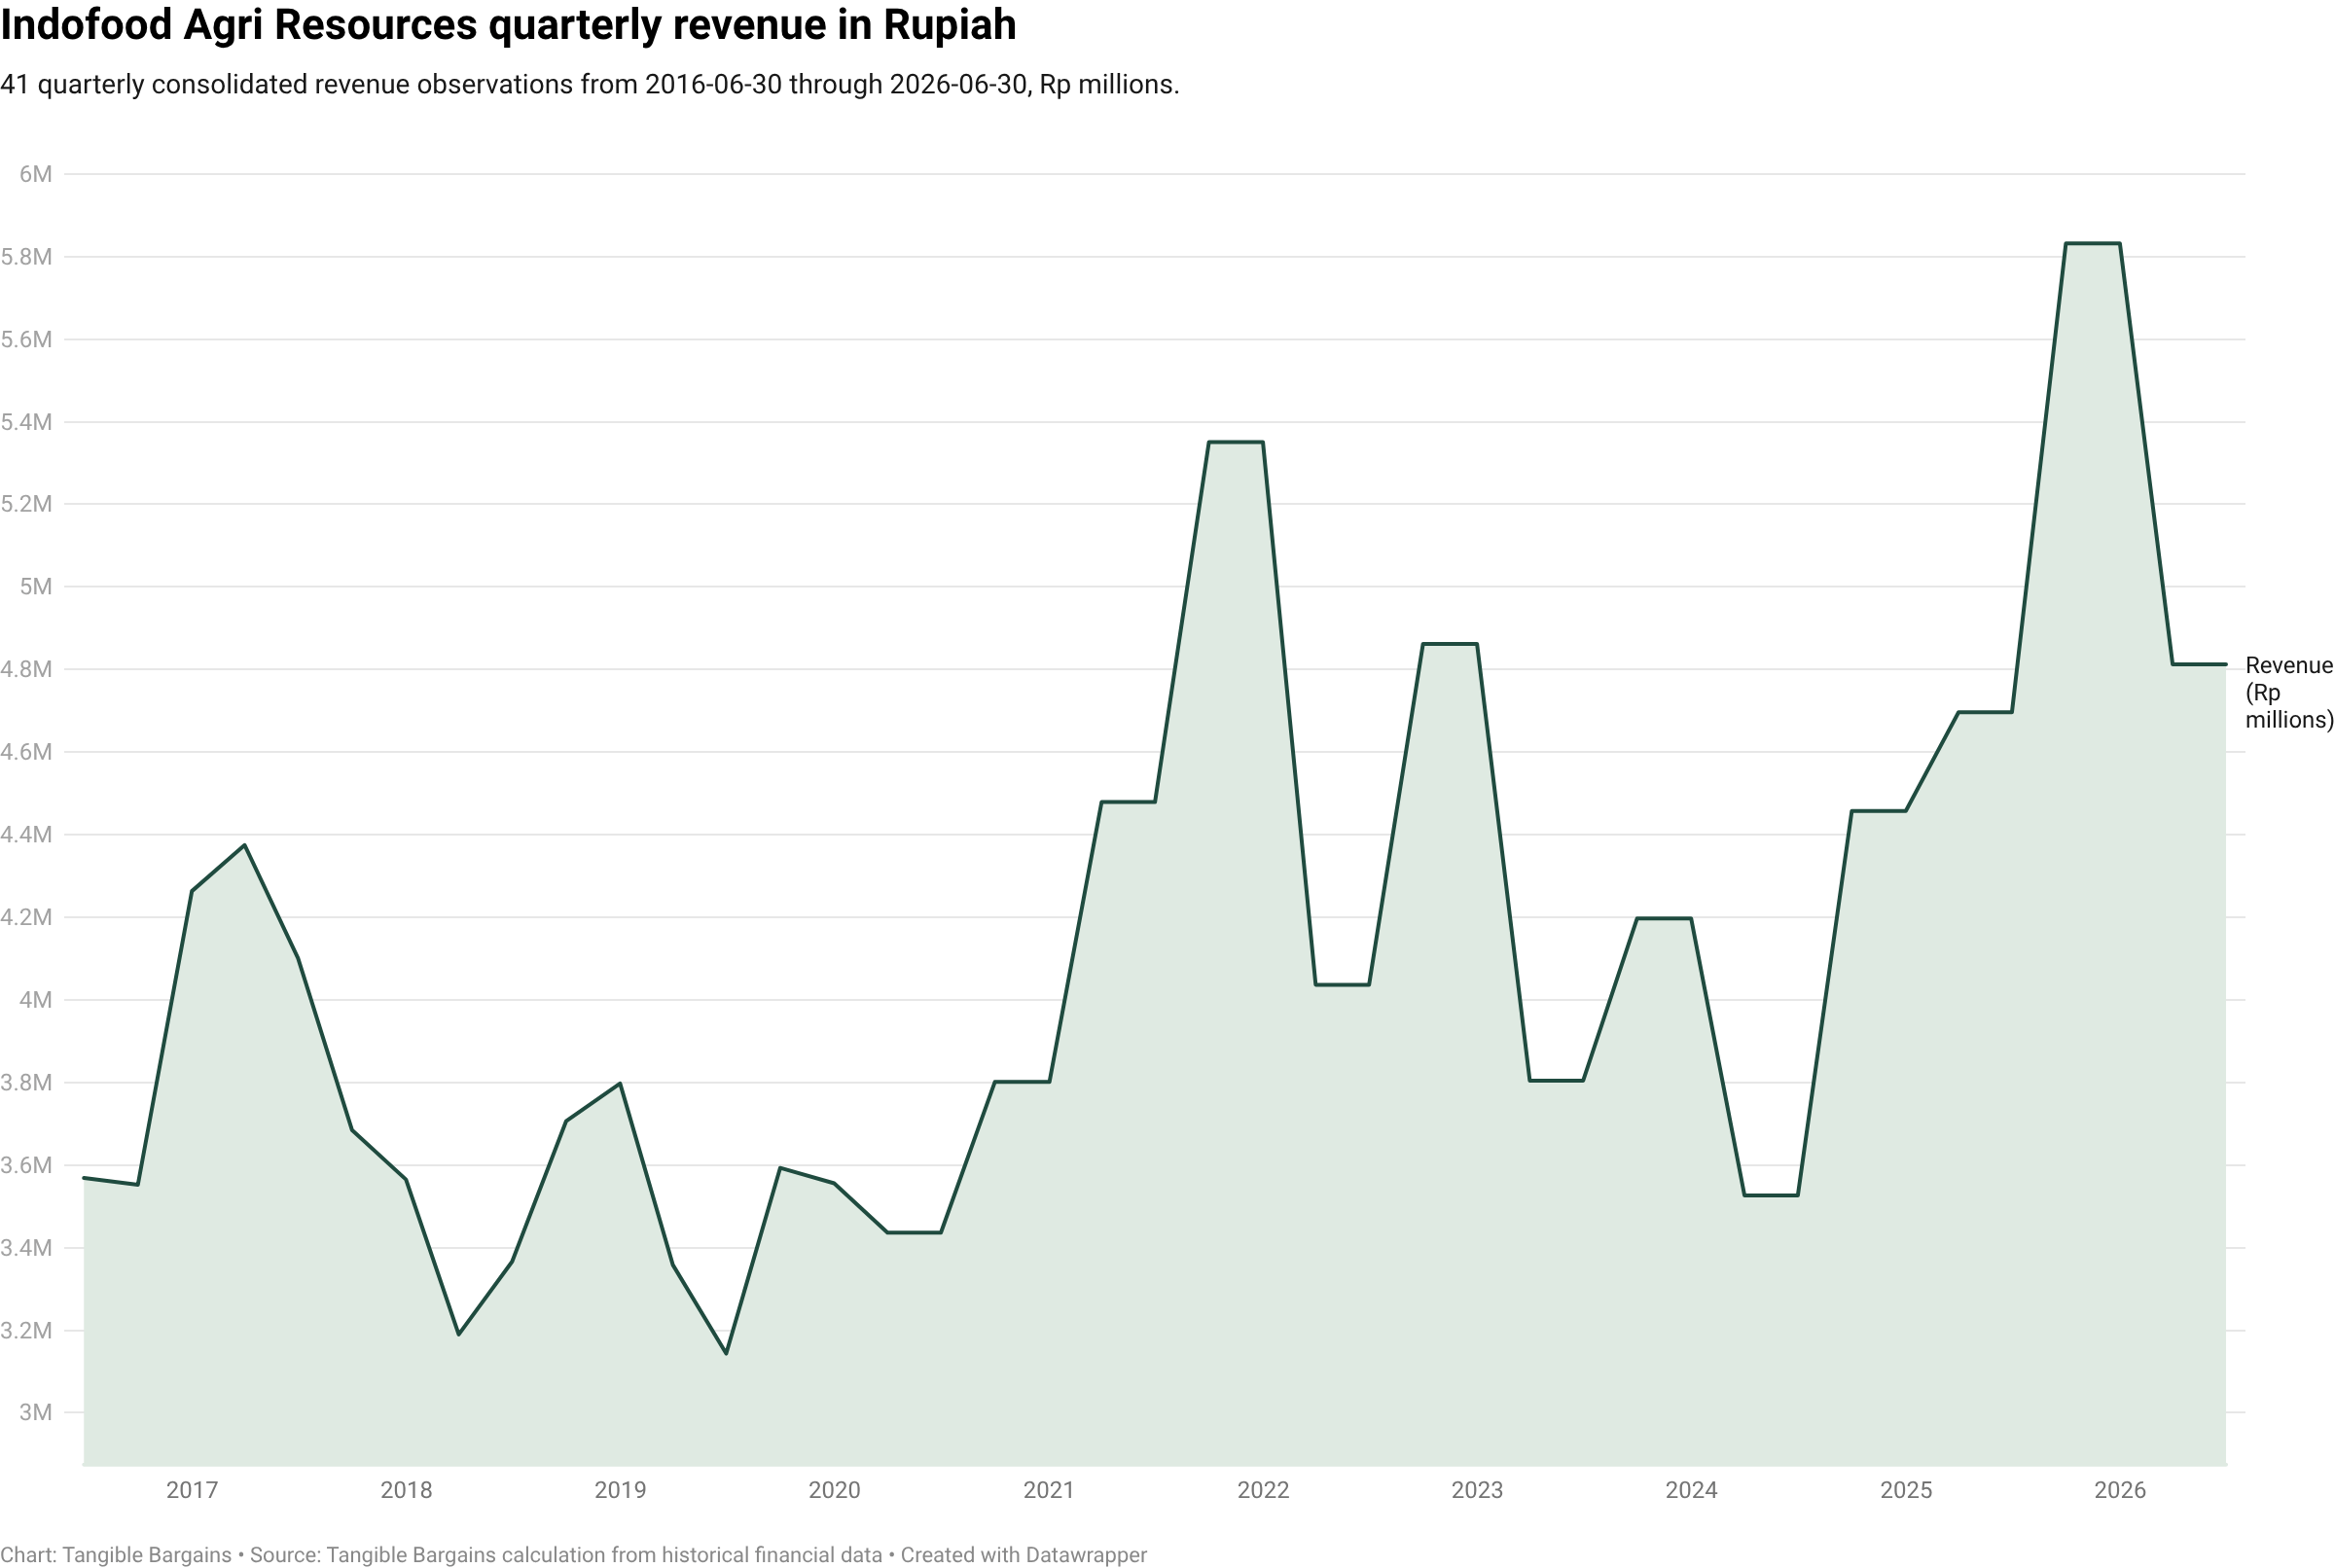
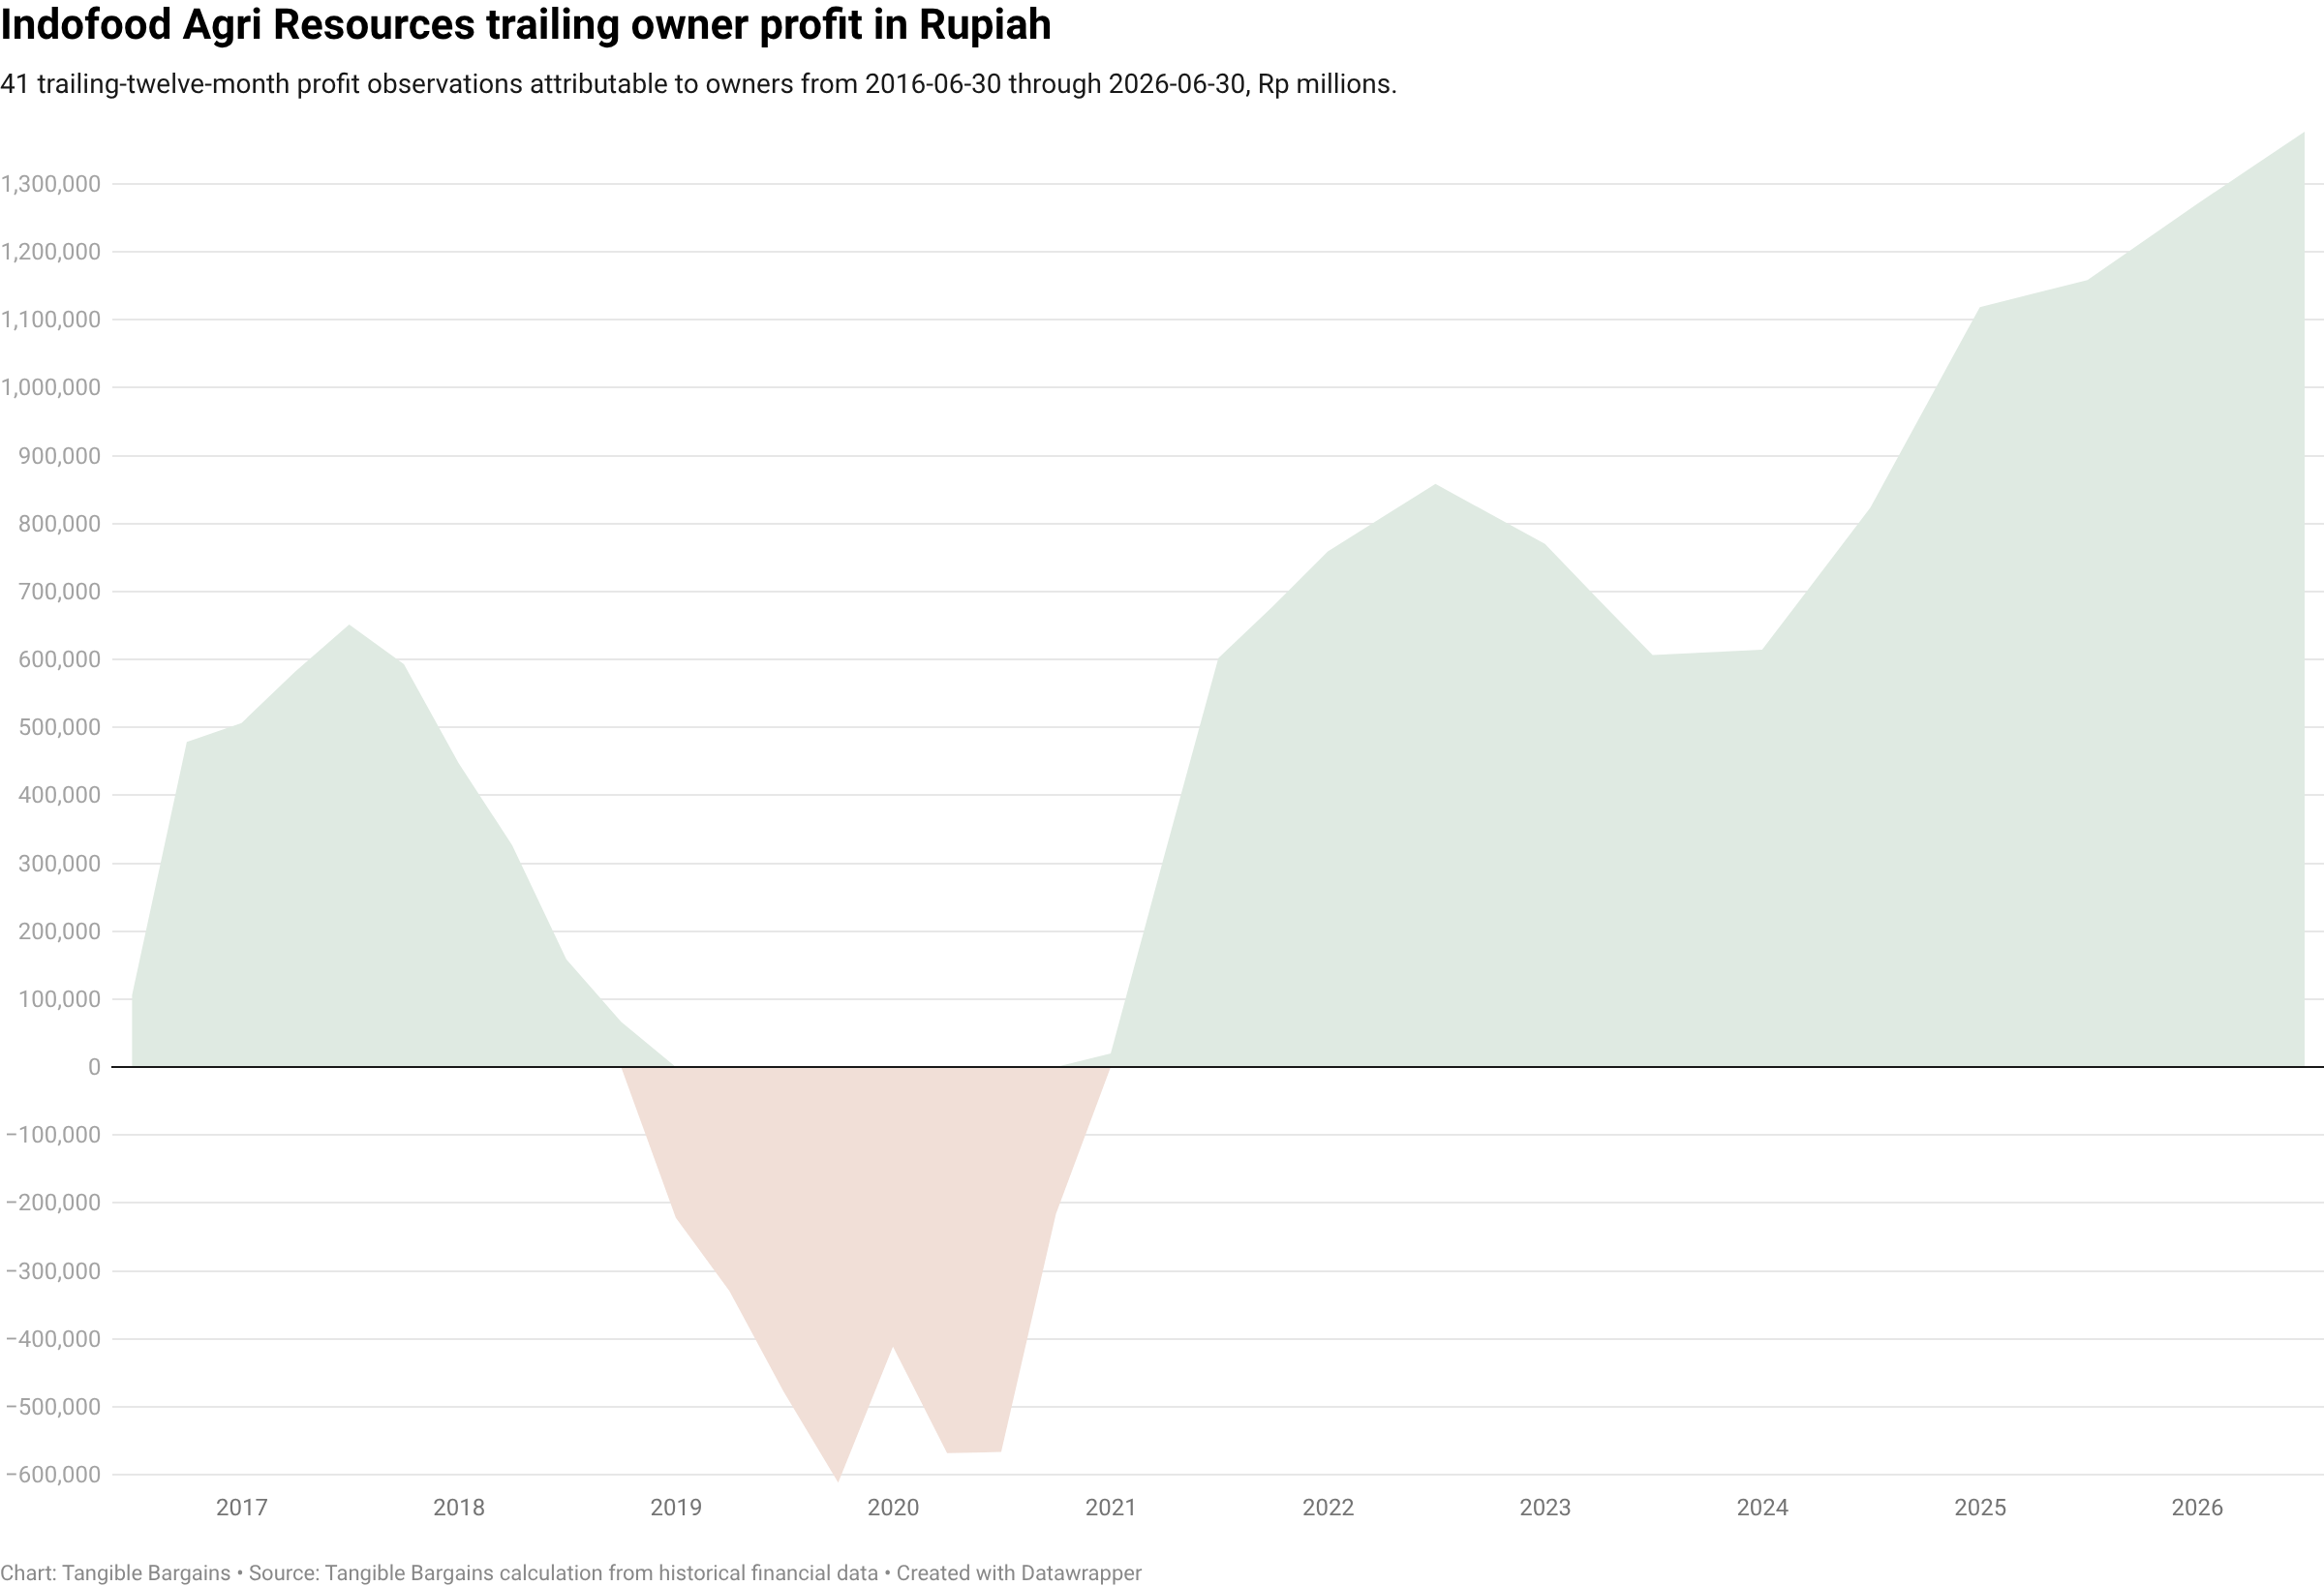
The recovery has substance. FY2025 operating cash flow of Rp3.38tn exceeded Rp1.44tn of capital additions, cash of Rp9.05tn almost matched Rp9.08tn of borrowings at June 2026, and first-half owner profit improved. The cycle is nevertheless cooling: gross margin fell from 29.8% in FY2024 to 25.6% in FY2025 and 22.4% in the latest half.
Control is the minority risk
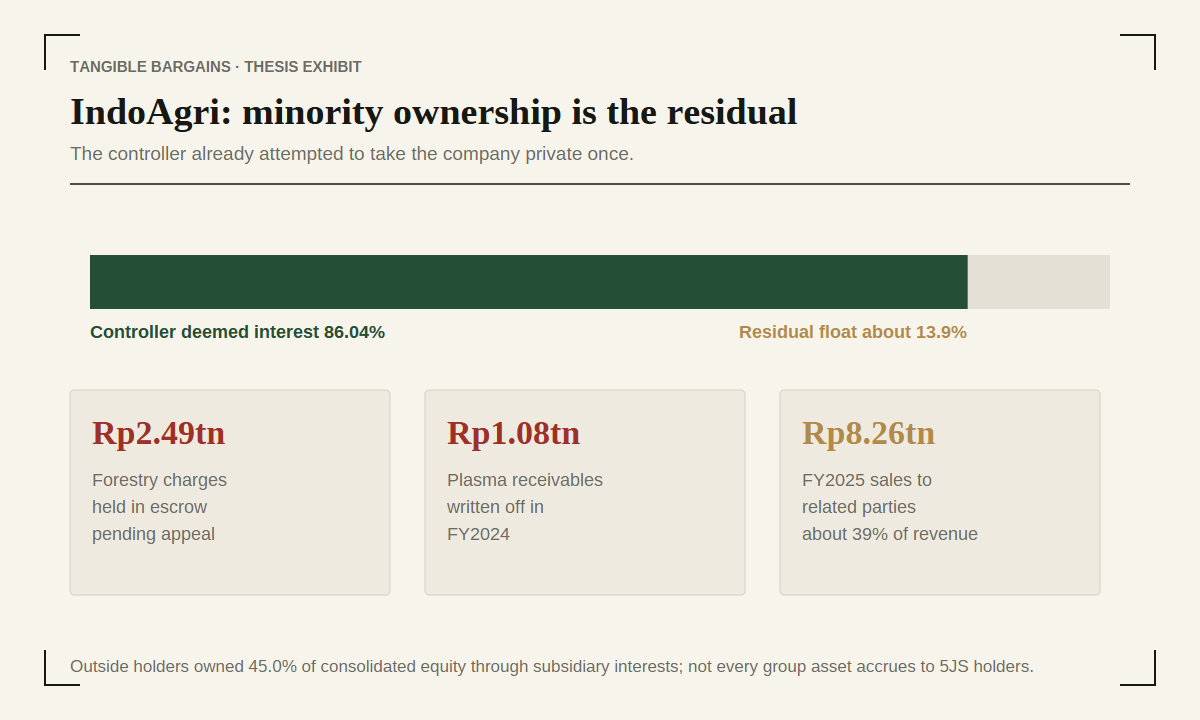
The controller, not the headline multiple, determines how much of the consolidated asset base can reach 5JS holders.
The Rp2.49tn forestry charge sits in escrow while under appeal, equal to 19.3% of tangible book. The plasma program has already produced a Rp1.08tn write-off and continuing charges. Related parties bought Rp8.26tn of FY2025 revenue. Non-controlling interests were 45.0% of group equity, and subsidiary minorities received more cash than IndoAgri shareholders in each period reviewed. Those are claims on the balance sheet, not footnotes to ignore.
What could change the view
The discount can close through a dividend, better margins, or evidence that the escrow and plasma obligations are shrinking. Fresh money still waits for S$0.282 because commodity risk, related-party dependence and controller realization risk are not paid for at S$0.325. A materially larger forestry loss, a call on the plasma guarantees, renewed leverage, or worsening related-party terms would make the balance-sheet case weaker.
Sources and gaps
The report uses the 2025 annual report, the six months ended 30 June 2026, AGM materials, SGX filings and public price history. FY2021–FY2022 audited statements were not retrievable for the supplementary cross-check; bank covenant headroom and inter-segment transfer prices remain undisclosed.
3. Numbers that matter
Derived tangible book is about S$0.669 per share. The current price is S$0.325, Buy-Below S$0.282, and Sell Range S$0.362–S$0.476. FY2025 revenue was Rp21.06tn; operating cash flow was Rp3.38tn against Rp1.44tn of additions. Cash and borrowings were Rp9.05tn and Rp9.08tn at June 2026. Subsidiary minorities were 45.0% of group equity. The forestry escrow was Rp2.49tn and the plasma write-off Rp1.08tn; related parties bought Rp8.26tn of FY2025 revenue.
Research only, not investment advice.