

1. Scorecard
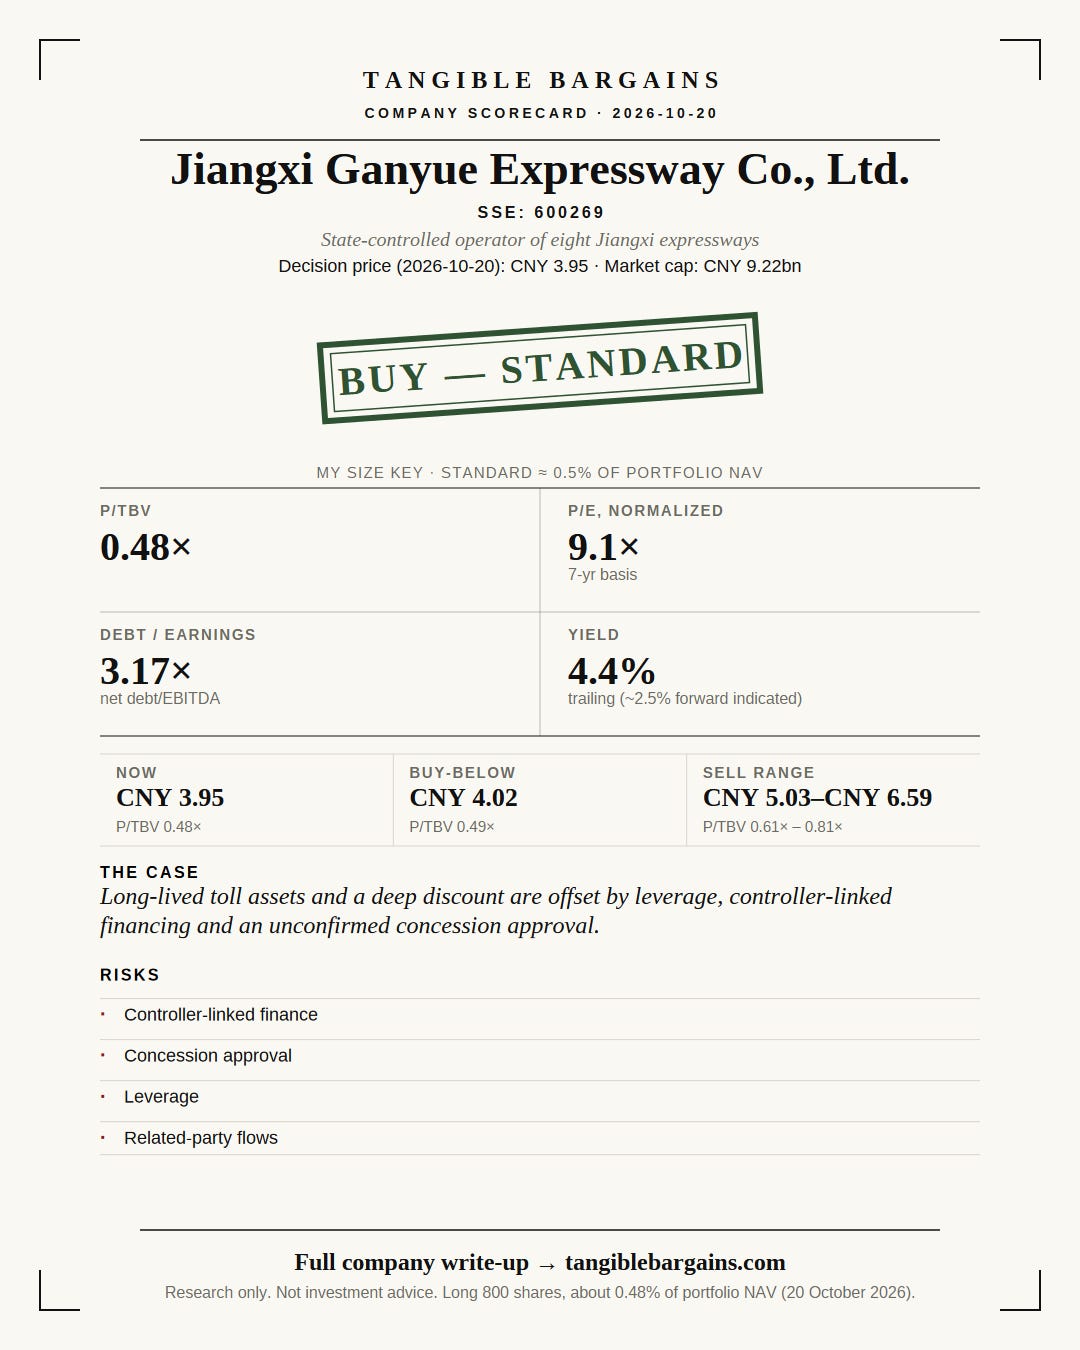
Verdict: BUY — STANDARD.
Actionable now: Yes — accumulate at ≤ CNY 4.02 (price CNY 3.95 as of 20 October 2026).
Position: Long 800 shares, about 0.48% of portfolio NAV (20 October 2026).
2. Argument
The short version
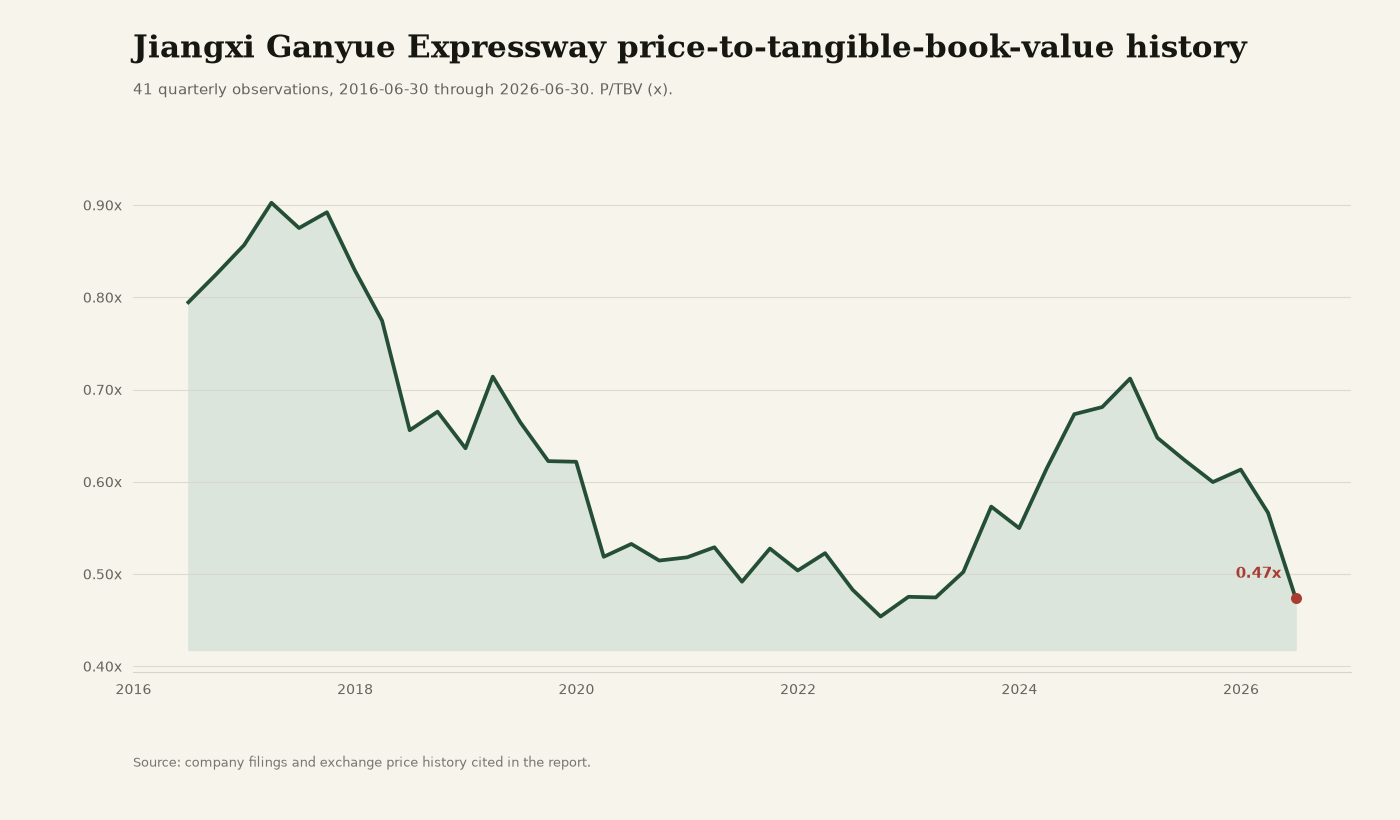
Jiangxi Ganyue operates eight state-controlled toll roads. At CNY3.95 on 20 October 2026, it trades near half of tangible book and just below the CNY4.02 Buy-Below. It is a standard-sized BUY because the roads are durable but the approval and governance chain is not settled.
Net debt is roughly equal to the market value of the equity, so the enterprise-level discount is smaller than the headline equity discount. CNY5.28bn of expansion work was capitalized in the first half on a concession whose reapproval is still unresolved.
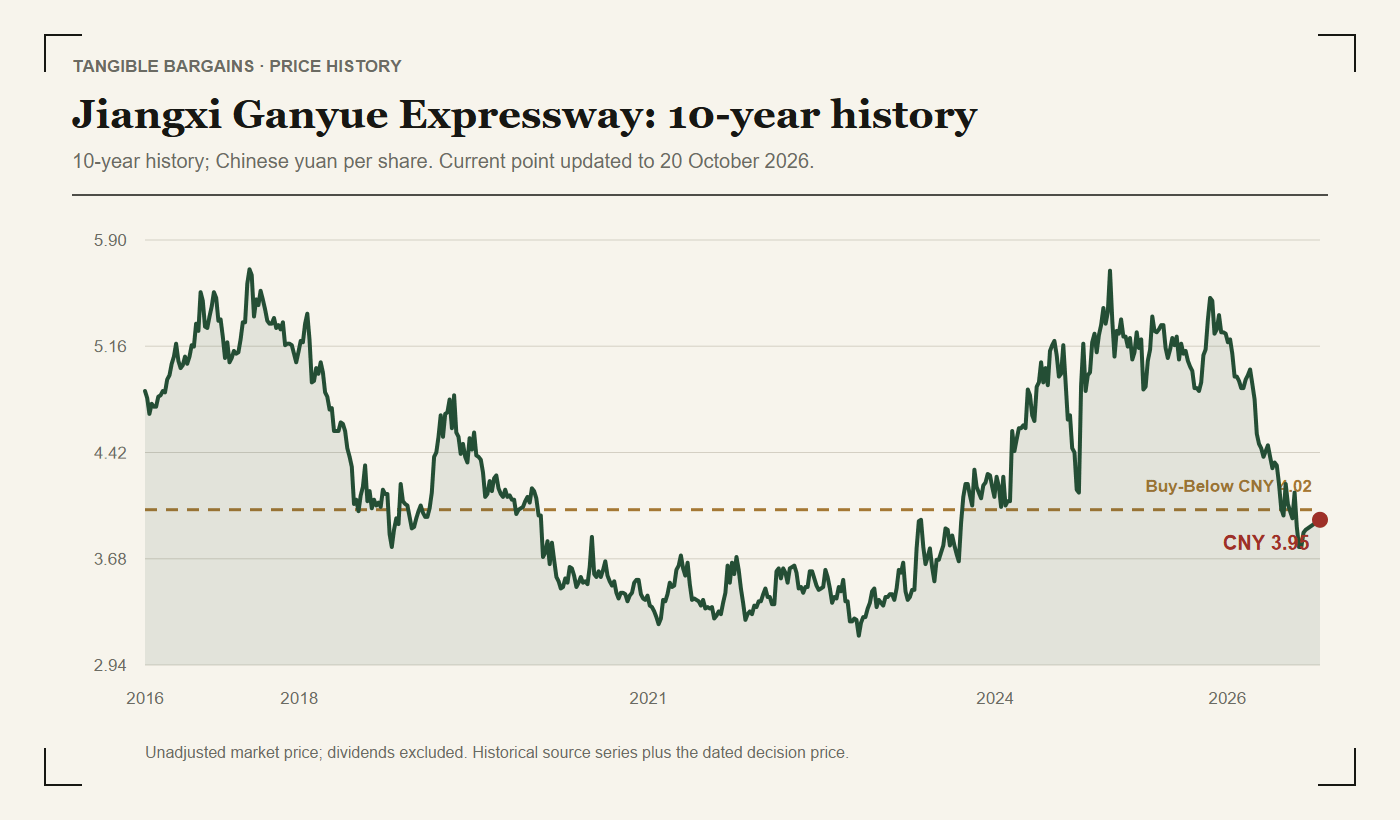
The ten-year history shows where the dated decision price sits. It is context for valuation, not evidence that a fallen share must rebound.
Long-lived roads, finite legal lives
The eight concessions run roughly seven to 23 years, with only one small road near expiry. Tolls provide recurring revenue, but construction creates value only if the concession term and toll framework allow the capital to be recovered. The company says it will apply to re-determine the Zhangji toll period; that approval is not in book value today.
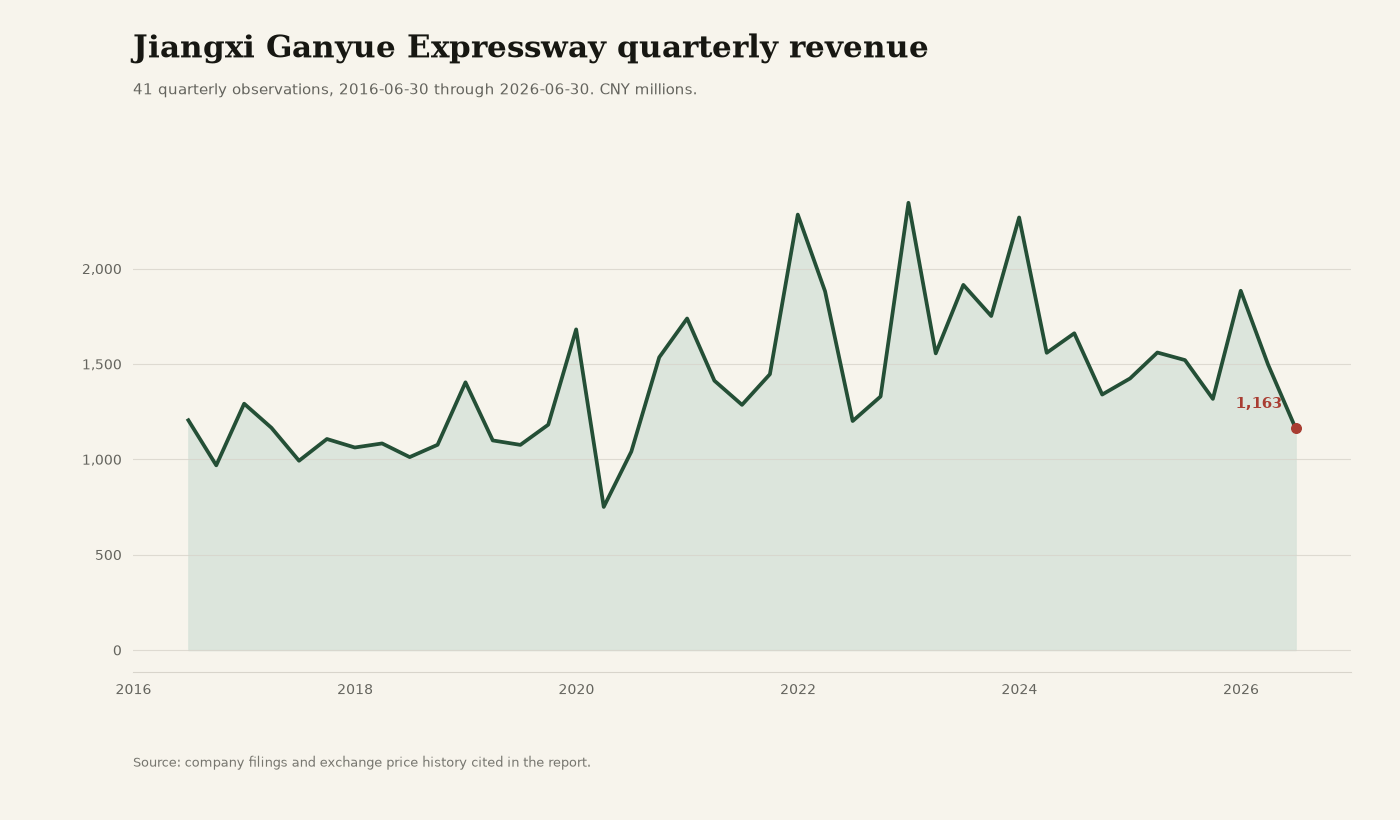
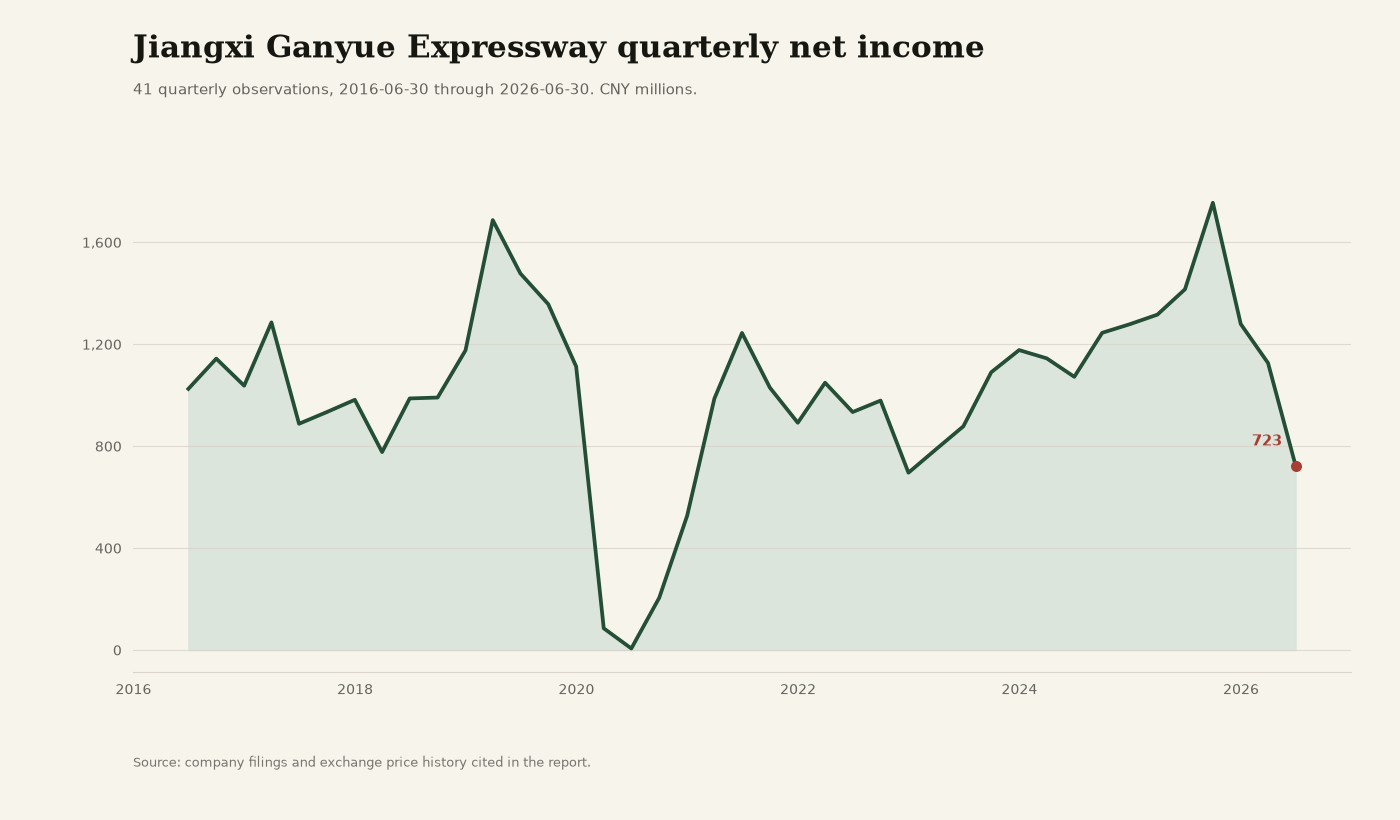
Reported profit is noisier than toll operations. A related-party brokerage position represented 96.7% of short-term investments and drove much of the latest fair-value loss. Road depreciation also depends on a management-commissioned traffic forecast; the 2026 estimate change reduced first-half profit by CNY37.94m and would have reduced each of 2023–2025 profit by roughly CNY120m.
The governance chain behind the roads
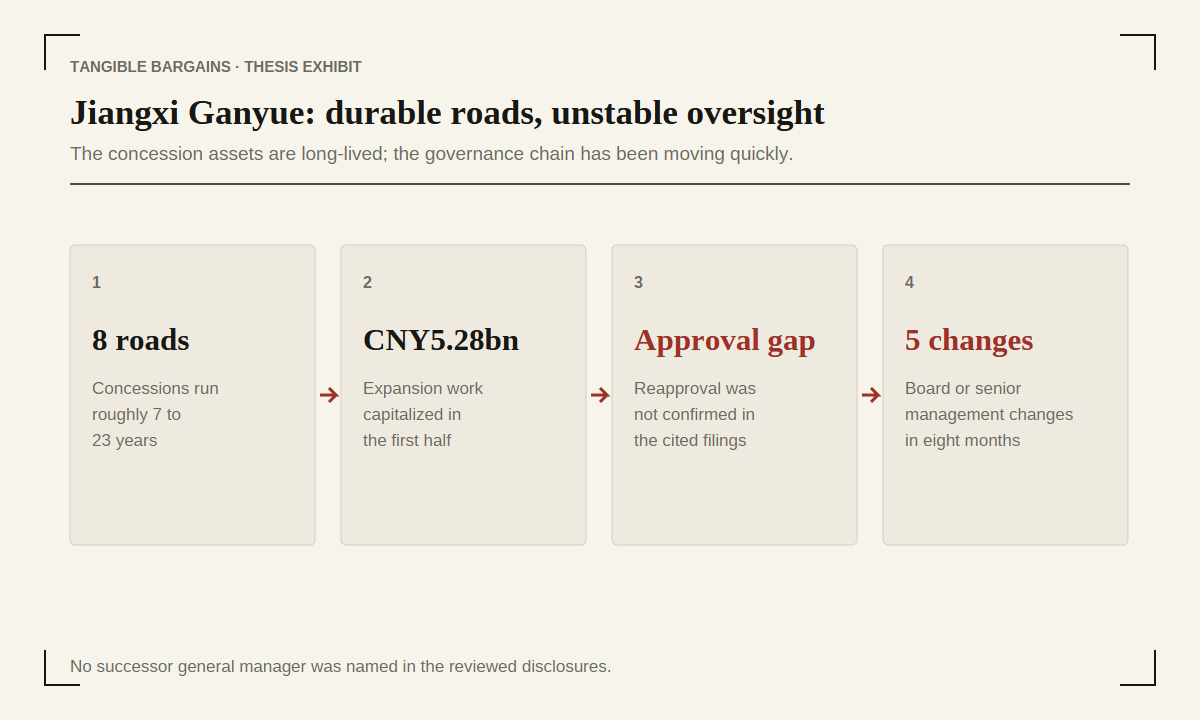
The roads have long lives; the financing, related-party and leadership record requires more filing-backed clarity.
The controlling shareholder owns 47.84%, operates the company's roads for CNY49.97m a year, holds CNY811.7m of group cash at its finance company, and sits on the other side of the CNY1.9899bn shareholder loan whose stated maturity was 7 September 2026. The report identifies a CNY110m ordinary-course related-party cap, but the larger balances and flows still need reconciliation.
What could unlock the discount
The low end of the Sell Range is CNY5.03, above the CNY4.02 Buy-Below. The path there is not heroic traffic growth: it is confirmation of the concession reapproval, clean treatment of the shareholder loan, reconciliation of related-party flows to the CNY110m cap, and evidence that new capital earns an acceptable return.
Sources and gaps
The report uses the company's H1 2026 and annual filings, a national credit-rating report, and exchange price history. The concession reapproval, January 2026 control change, post-maturity loan status and related-party reconciliation remain open. The filings disclose a CNY110m ordinary-course cap; larger related-party balances and flows are not reconciled in the available disclosures.
3. Numbers that matter
The current price is CNY3.95, Buy-Below CNY4.02, and Sell Range CNY5.03–6.59; tangible book per share is about CNY8.19. Eight concessions run seven to 23 years. CNY5.28bn was capitalized on an expansion whose reapproval remains open. The traffic reforecast reduced first-half profit by CNY37.94m and would have reduced each of 2023–2025 profit by roughly CNY120m. Related-party flows must be reconciled to the CNY110m ordinary-course cap; the CNY1.9899bn shareholder loan's post-maturity treatment remains unconfirmed.
Research only, not investment advice.