

1. Scorecard
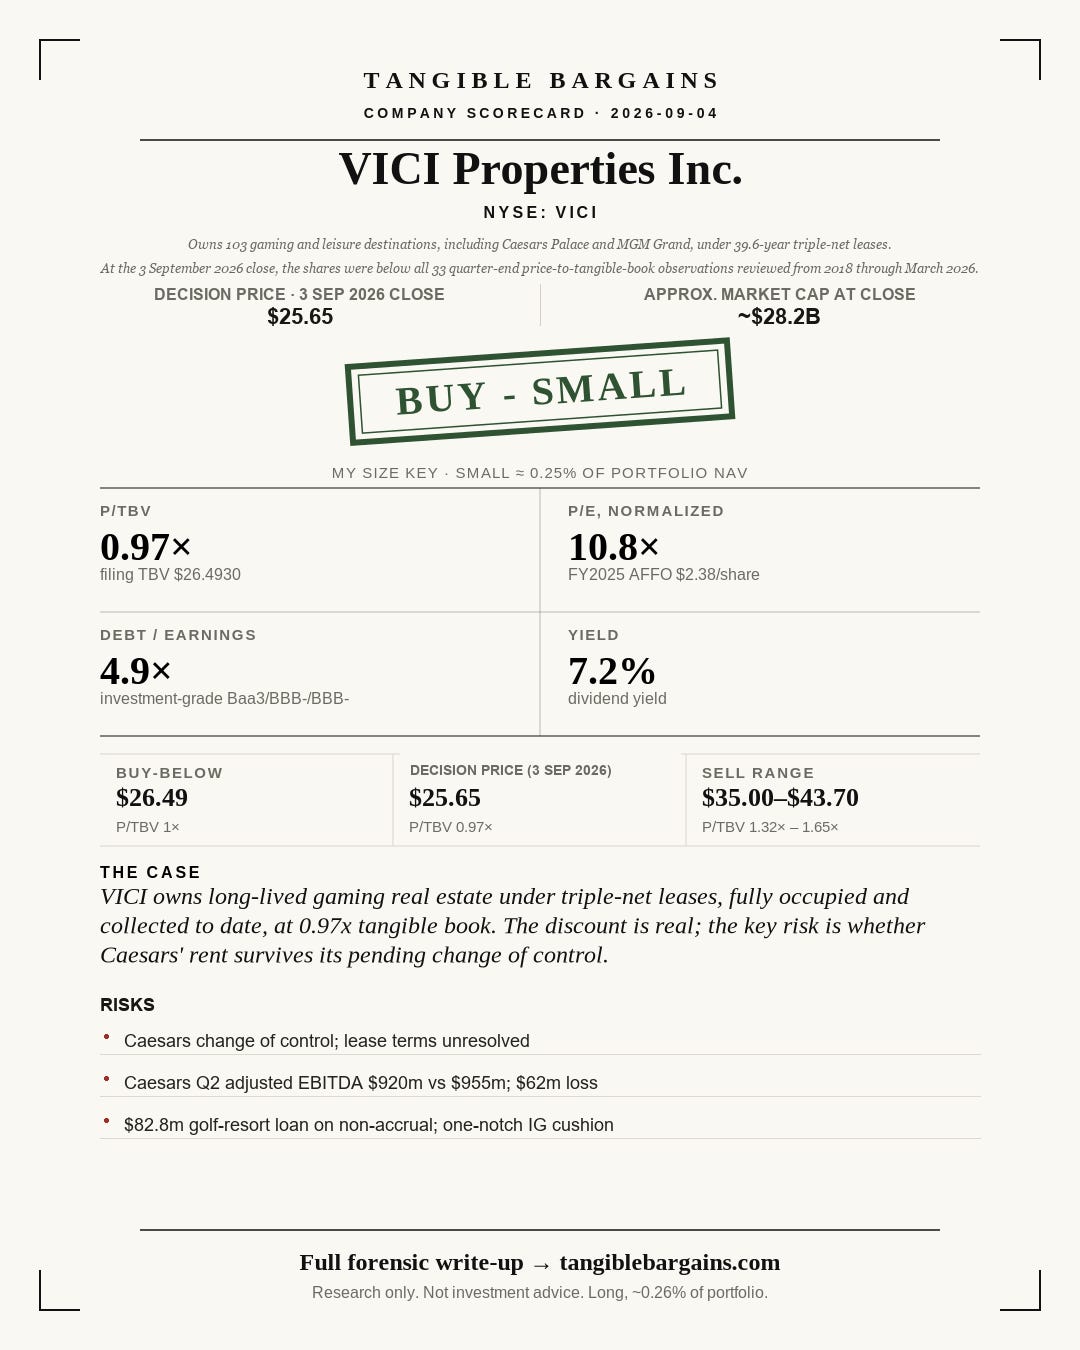
Verdict: BUY — SMALL.
Actionable now: Yes — as of 3 September 2026 close; the decision price was $25.65. Accumulate at or below $26.49.
Position: Long, about 0.26% of portfolio at the 4 September 2026 report date.
This is a historical investment case based on information reviewed on 4 September 2026. It records the decision at that time and is not a present-day price assessment.
2. Argument
The short version
VICI owns long-lived gaming real estate leased to operators under tenant-funded contracts. The BUY-SMALL case rested on full occupancy and rent collection, a growing dividend, and an entry price below tangible book. The main uncertainty was whether Caesars' rent would remain intact through its pending change of control, not whether the properties could be occupied.
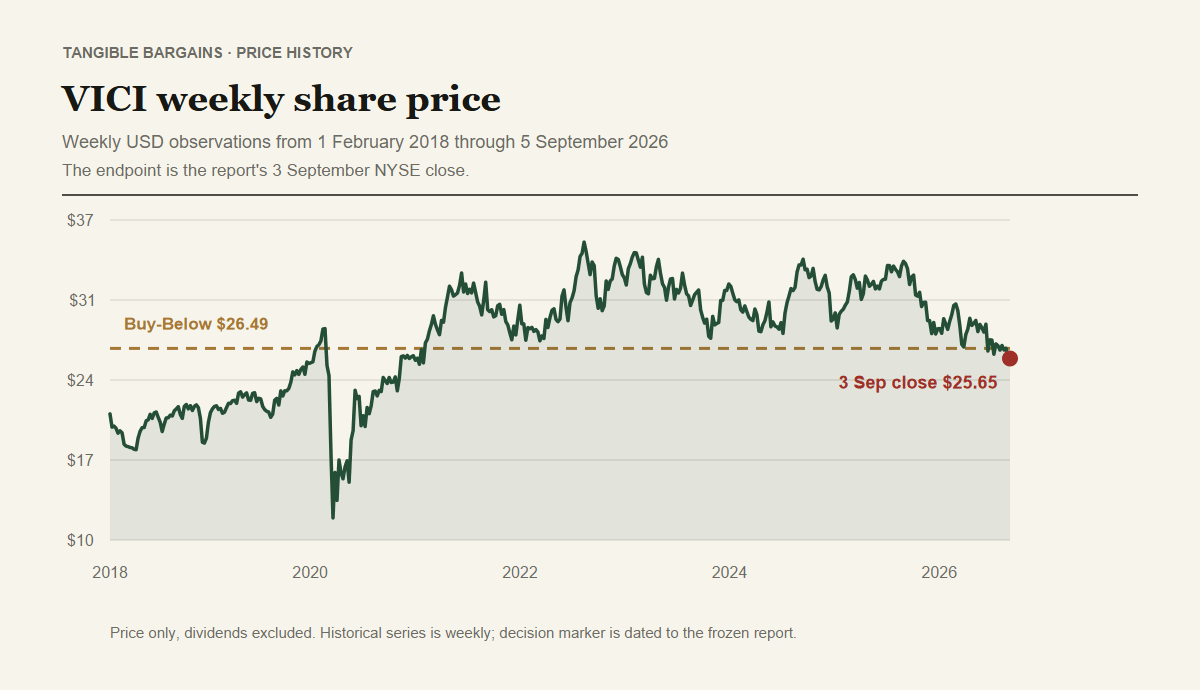
Endpoint: 3 September close. Price return excludes dividends.
The lease contract is the business
VICI is a landlord, not a casino operator. It leases 103 destinations to 16 tenants under triple-net contracts: tenants pay taxes, insurance, maintenance, and capital spending. Weighted lease term including options was 39.6 years. Occupancy and rent collection were 100% since 2017, including through the pandemic. Parent guarantees support the Caesars and MGM leases, but tenant credit remains the key risk.
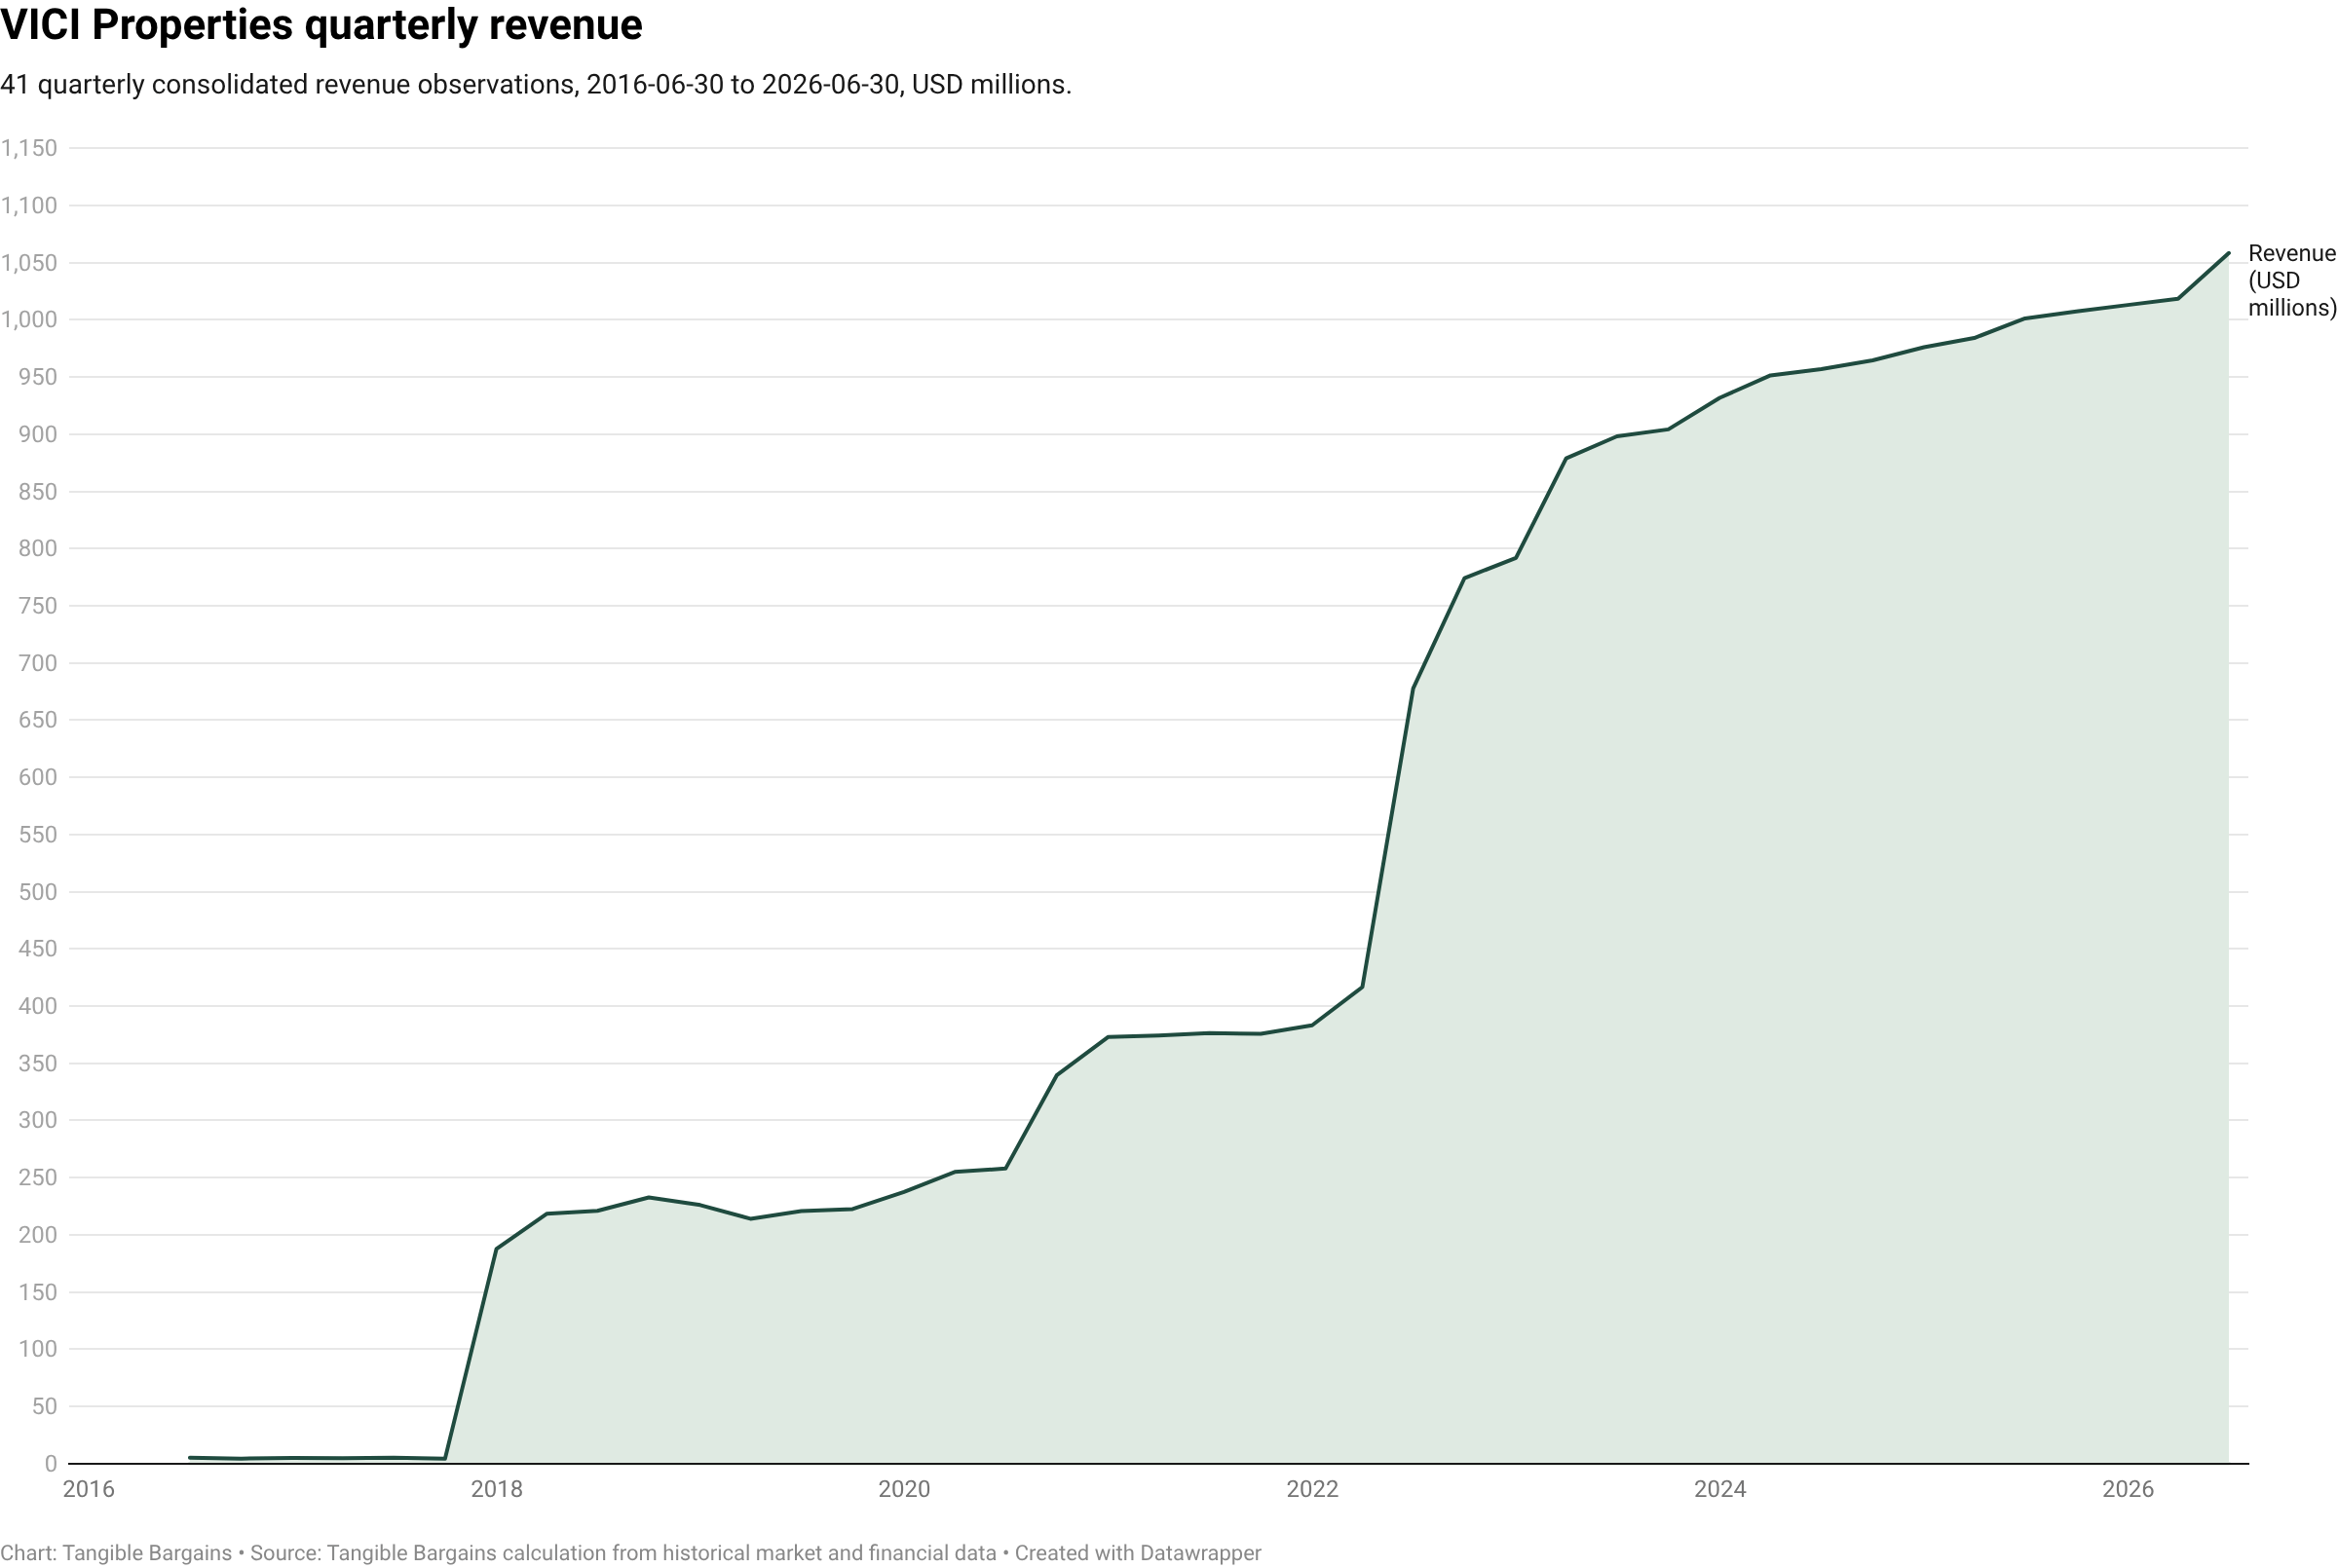
Revenue through Q2 2026. AFFO, VICI's adjusted cash-earnings measure for a REIT, is used here to assess dividend capacity.
The yield comes with concentration
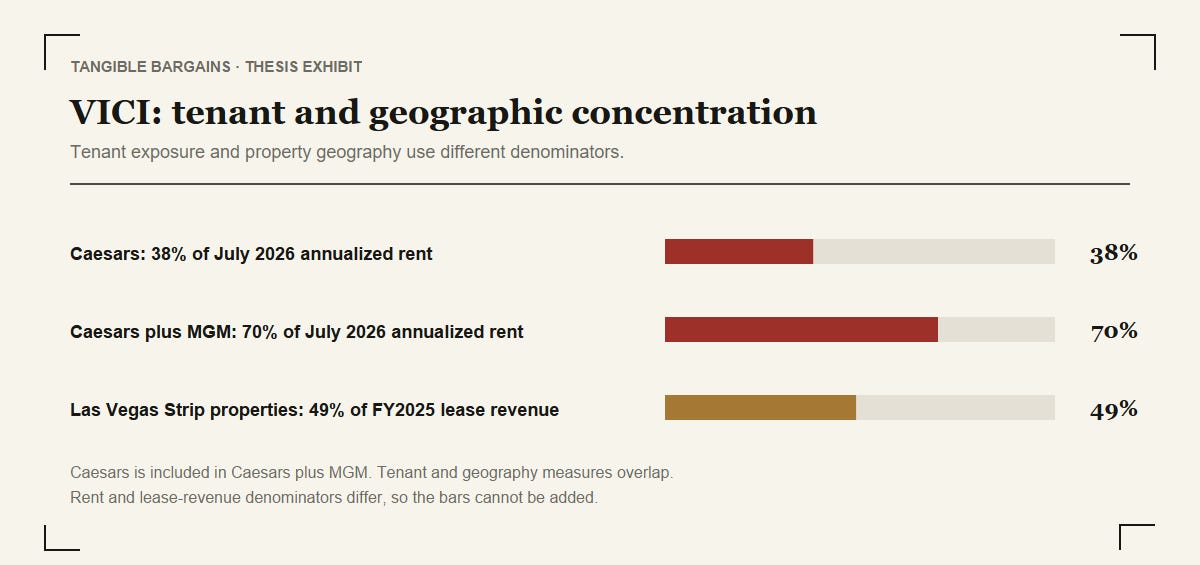
Caesars supplied 38% of July 2026 annualized rent; Caesars plus MGM supplied 70%. The Strip was 49% of FY2025 lease revenue. Caesars is included in the combined tenant figure. These exposures overlap and use different denominators, so the bars cannot be added.
Caesars agreed to a Fertitta take-private in May 2026, but VICI gave no timeline for lease discussions. Caesars' Q2 adjusted EBITDA fell to $920 million from $955 million a year earlier, with a $62 million net loss. Guarantees mitigate, but do not resolve, the rent-reset risk.
Cash generation and financing
FY2025 operating cash flow was $2.51 billion against $1.3 million of property capital spending because tenants fund upkeep. Adjusted funds from operations (AFFO), VICI's adjusted cash-earnings measure for a REIT, was $2.38 per share, with 2026 guidance of $2.45 to $2.47. Annualized dividend: $1.84 per share.
Since most cash is distributed, acquisitions require debt or equity. VICI had slowed share issuance below book; its share count rose 75% since FY2021. Borrowings were $16.9 billion, net debt to EBITDA 4.9 times, and the three investment-grade ratings had one notch of cushion above high yield.
The Q2 filing carried a $1.93 billion credit-loss allowance. An $82.8 million senior secured golf-resort loan went on non-accrual in Q4 2025, meaning interest stopped counting as current income because collection was uncertain. It was VICI's first disclosed credit event and was small relative to the portfolio.
Valuation and payoff
Price to tangible book (P/TBV) compares share price with tangible book per share. VICI's 3 September 0.968x mark was below the lowest of 33 quarter-end observations in the eight-year series, not itself a quarter-end point. The comparison is context, not a promise of reversion.
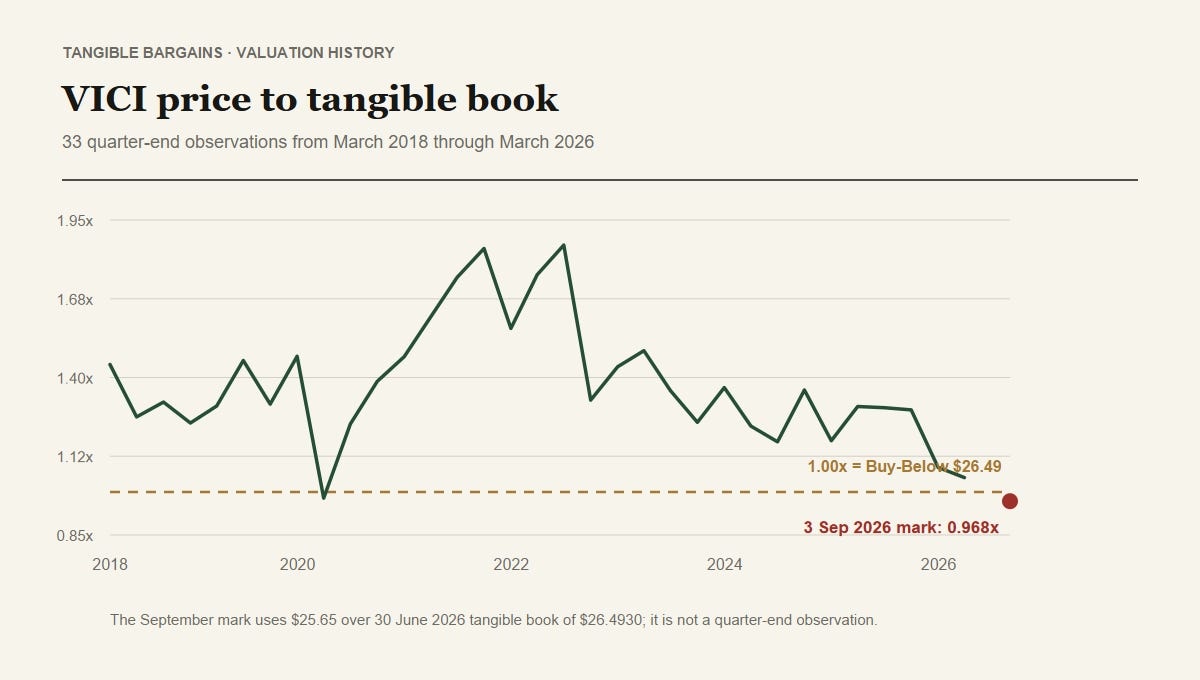
Quarterly series through 31 March 2026. The separate September mark uses the decision close and 30 June tangible book.
The $26.49 Buy-Below equaled one times tangible book. The historical Sell Range was $35.00 to $43.70; its $35 low end was conditional on sound tenant credit and a more normal rent valuation, not a promised target. The dividend was the main return while waiting.
What would change the view
A Caesars rent cut, a downgrade below investment grade, or a second non-accrual loan would weaken the thesis.
Issuing shares below tangible book would dilute holders and reverse VICI's below-book issuance restraint.
At report time, Q3 results were expected in late October. Monitor Caesars lease terms, the allowance, and the loan.
Sources and gaps
The FY2025 10-K and Q2 2026 10-Q were read in full. The 2026 proxy's compensation and audit-fee schedules were not read in full; its related-party section was checked through policy and negative disclosure, not line by line. VICI is lender, landlord, and prospective buyer to golf-course manager Cabot; no off-market arrangement was disclosed. The historical P/TBV series behind the Sell Range was not rebuilt against each filing.
3. Numbers that matter
Historical decision date: 3 September 2026 close, $25.65. Report date: 4 September 2026. Market capitalization: approximately $28.2 billion. Filing tangible book: $26.4930 per share at 30 June 2026. Price to tangible book: 0.968x. FY2025 adjusted funds from operations (AFFO): $2.38 per share; 10.8 times AFFO. Annualized dividend: $1.84 per share; 7.2% yield at the decision price. Buy-Below: $26.49. Sell Range: $35.00 to $43.70. Position at report date: Long, about 0.26% of portfolio NAV.
Sources include VICI's FY2025 Form 10-K, Q2 2026 Form 10-Q and supplement, 2026 proxy statement, Q2 2026 earnings release and earnings call, Caesars' Q2 2026 earnings release, and the historical market and valuation series. All figures are in US dollars unless stated otherwise.
Research only, not investment advice.